Listed by Jason LaFlesch, Results Realty · Financing by Mike Barnhart, Swift Mortgage
Gilbert, AZ 85298 · The Bridges at Gilbert · Bridges North
3874 E Strawberry Dr, Gilbert, AZ 85298
A single-level Meritage home in Bridges North with a private pool, a true split floorplan, and no one behind you, now offered at $749,000. Structured with a 2% seller concession, an offer on this home can fund a 2-1 buydown that starts the buyer's payment hundreds of dollars lower for the first two years.
$749,000
4 bed3 bath2,411 sq ftSingle-storyPrivate pool3-car garage2.00% concession · $14,980 · can fund a 2-1 buydown
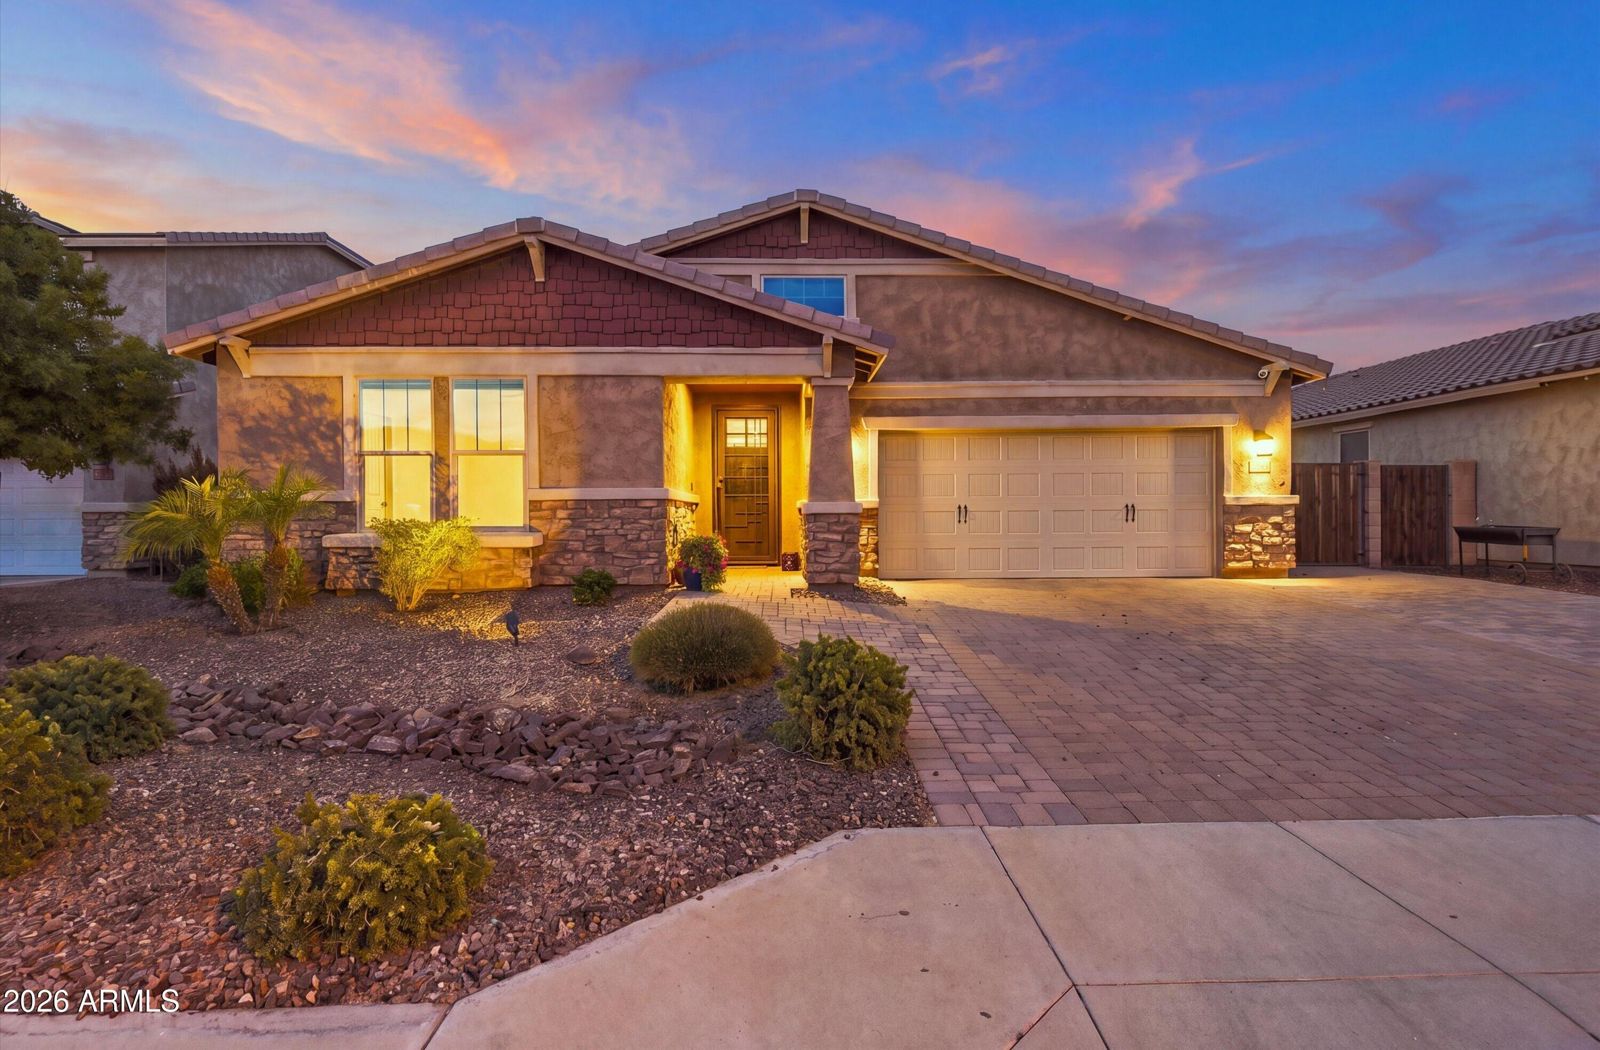
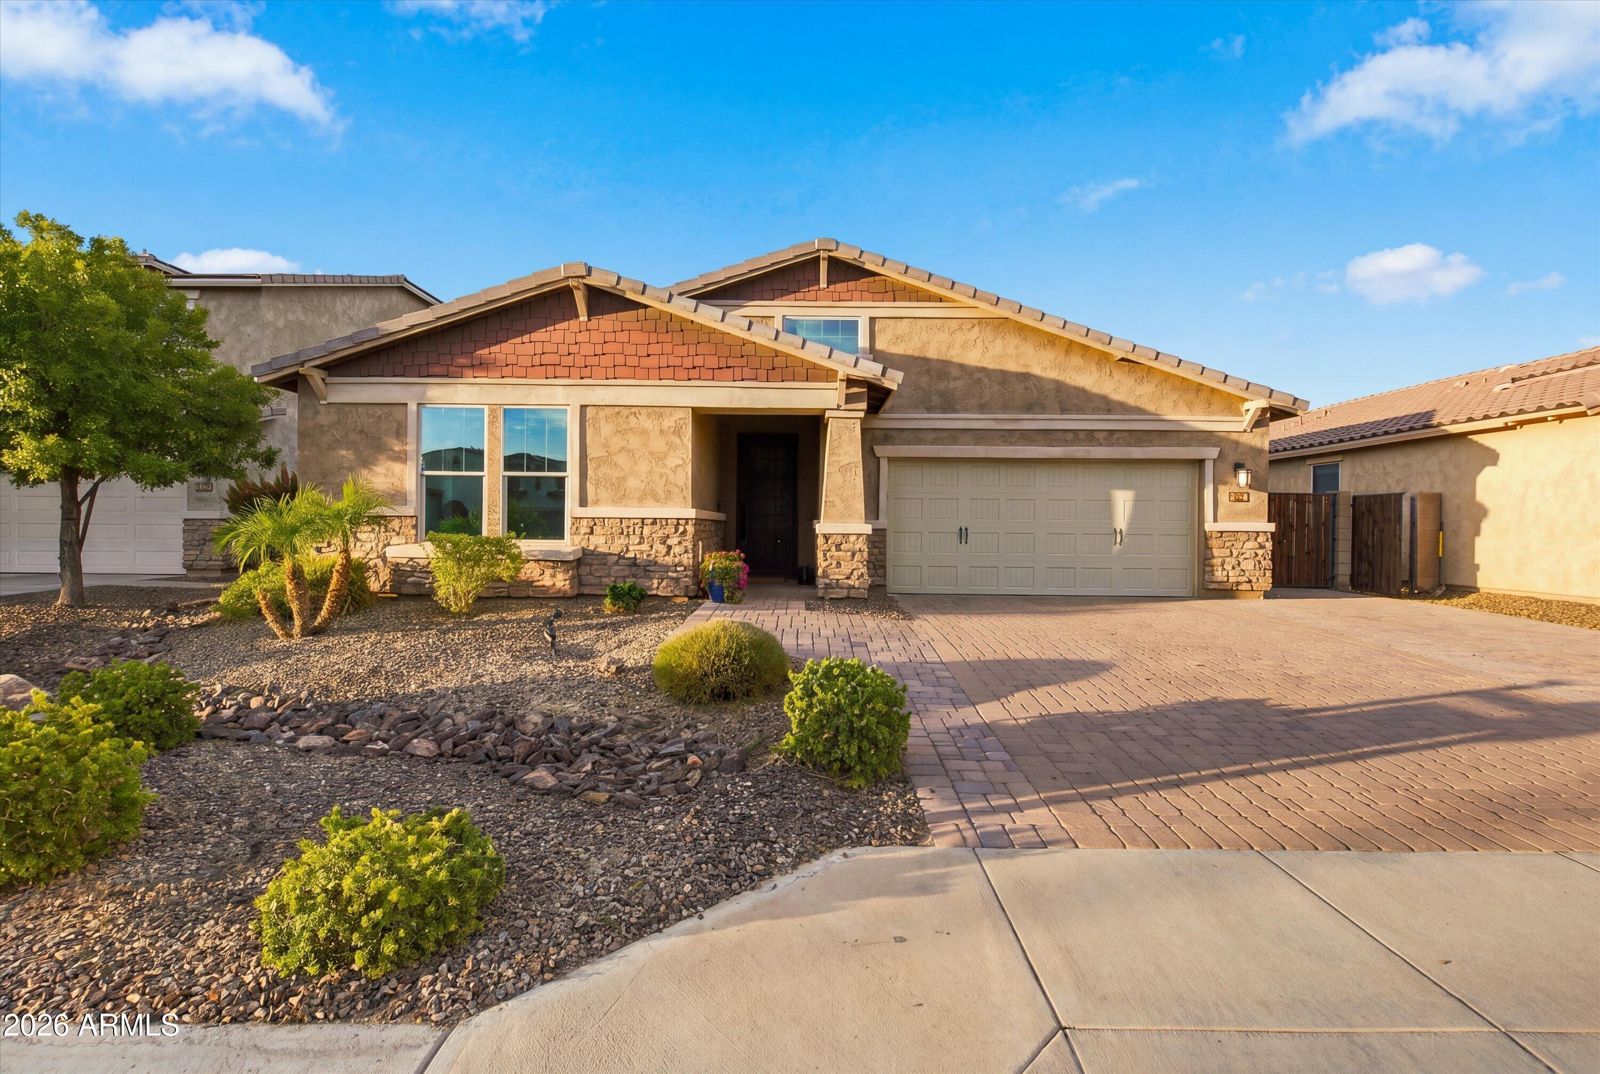
3874 E Strawberry Dr, Gilbert. Listing photo, ARMLS.
List price
$749,000
Listed October 21, 2026 with Results Realty, ARMLS #7096736.
The home
4 bd · 3 ba · 2,411 sf
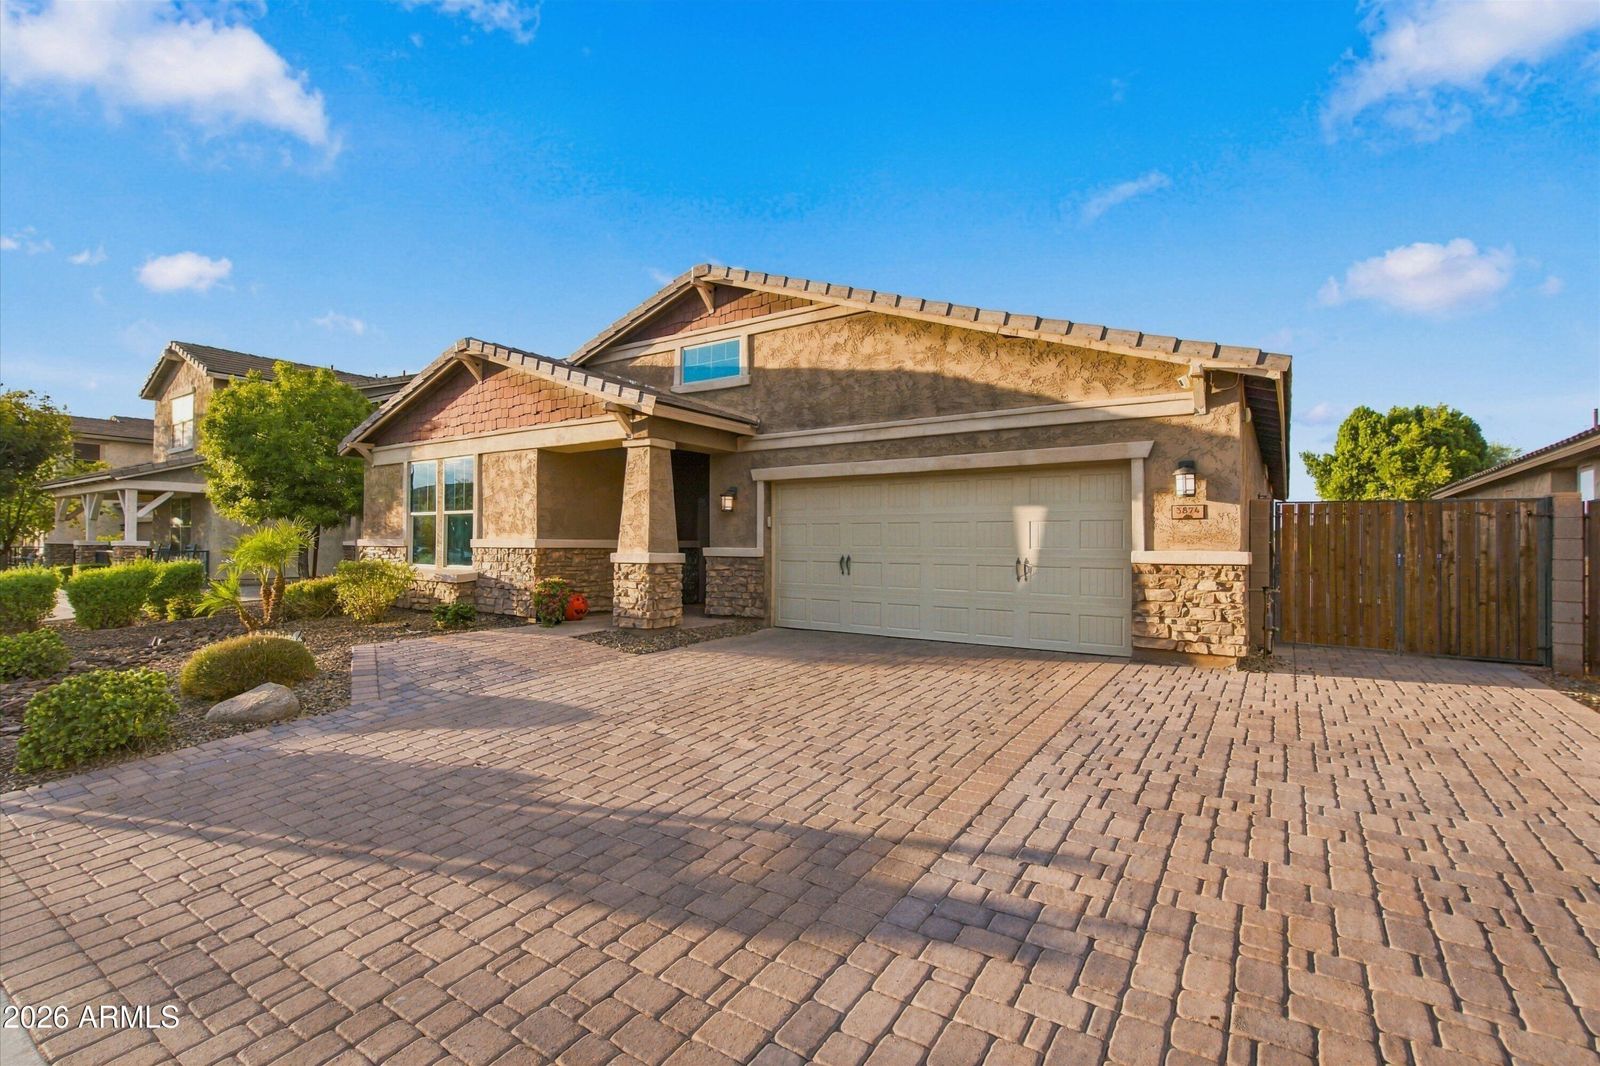
Single-level Meritage home built in 2015, split floorplan with a huge flex room, private pool, and a 3-car garage.
The financing angle
$14,980
A 2.00% seller concession written into an offer, enough to fund the 2-1 buydown featured below.
Photos of this home
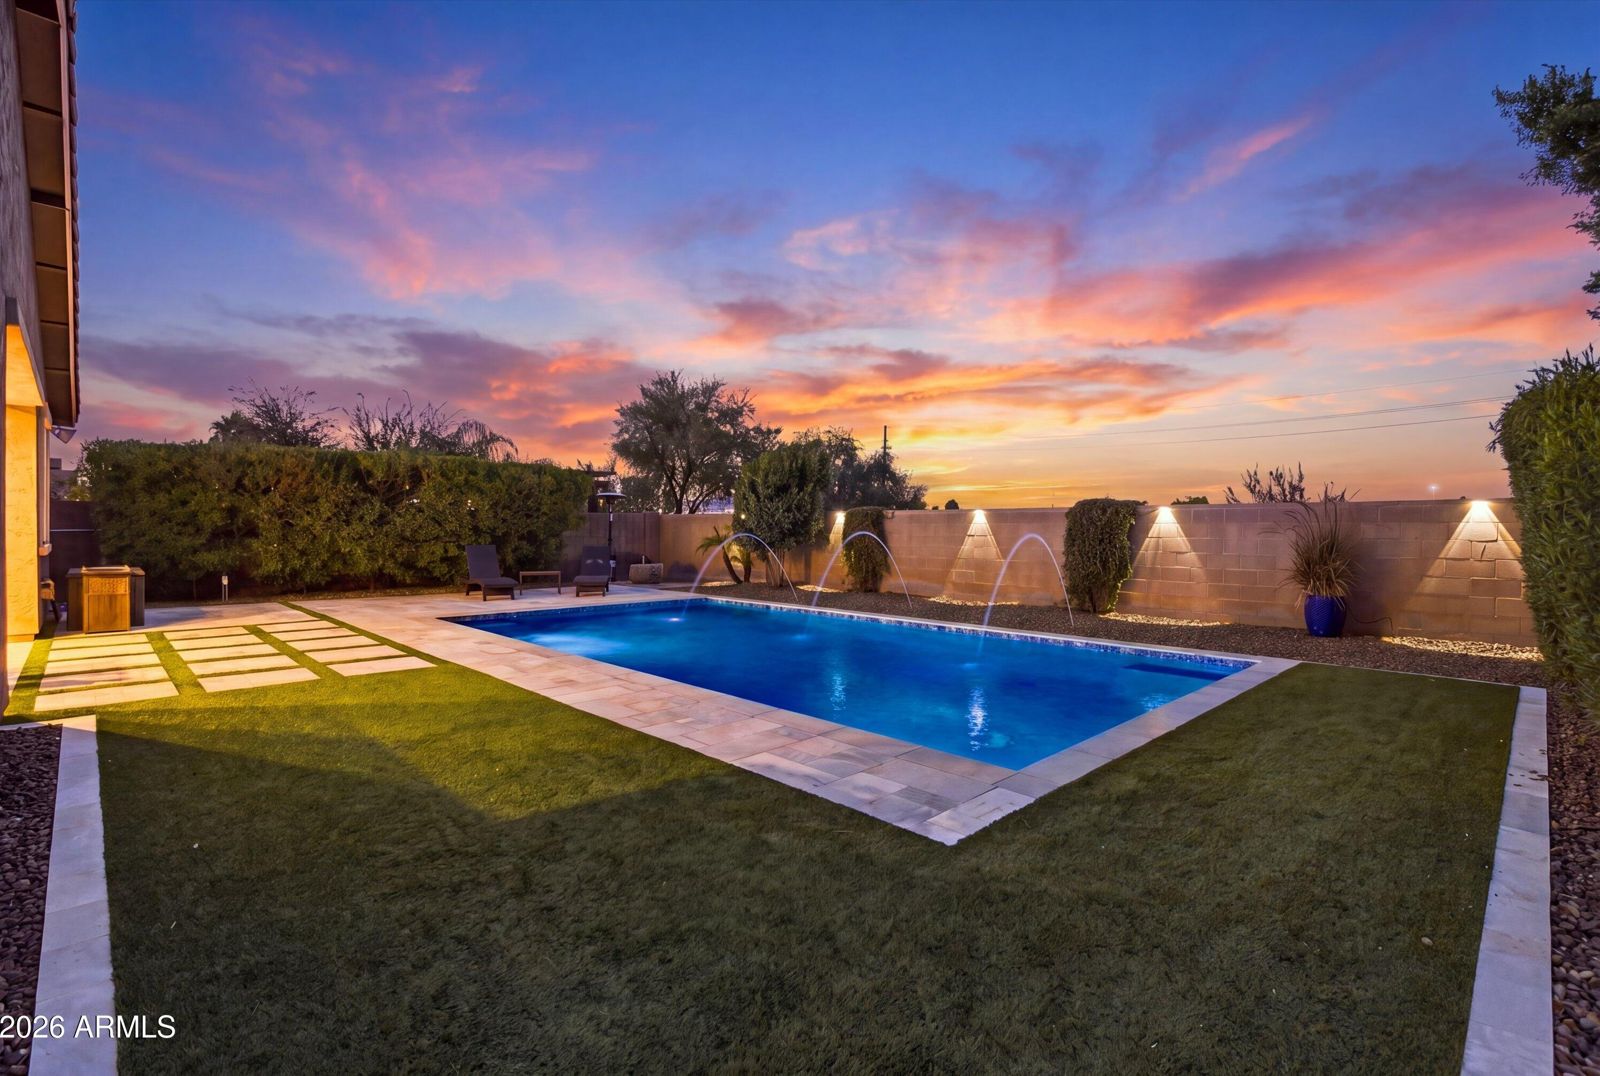
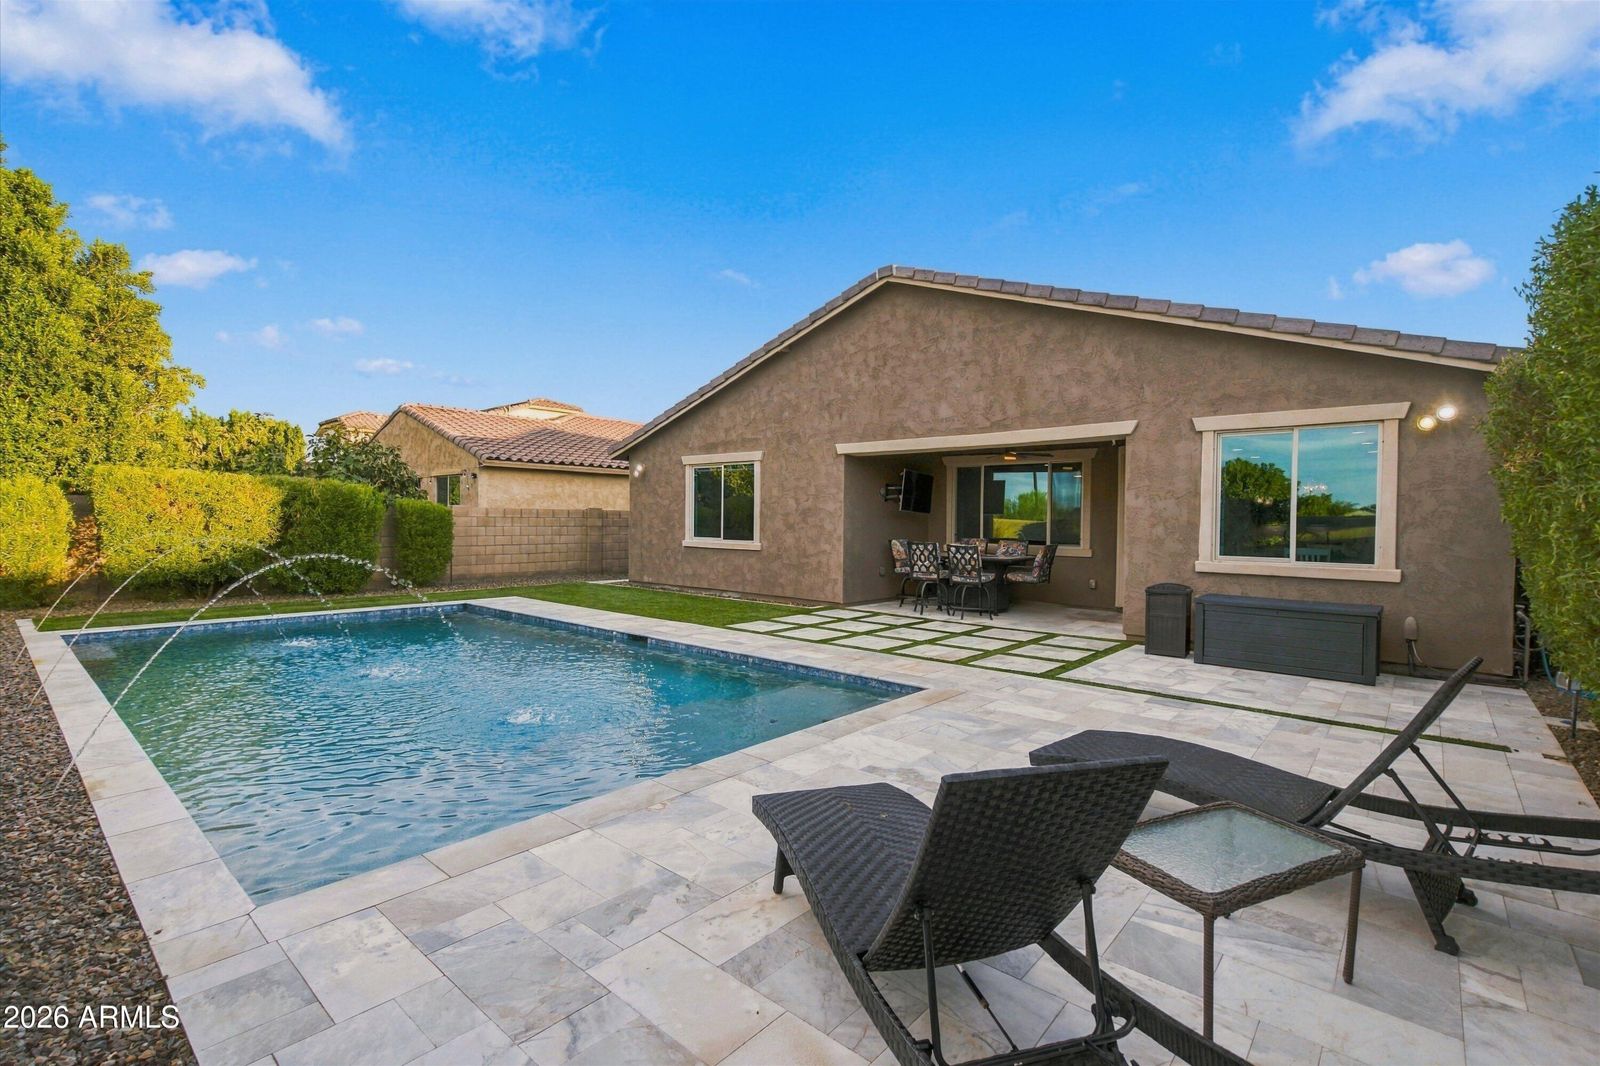
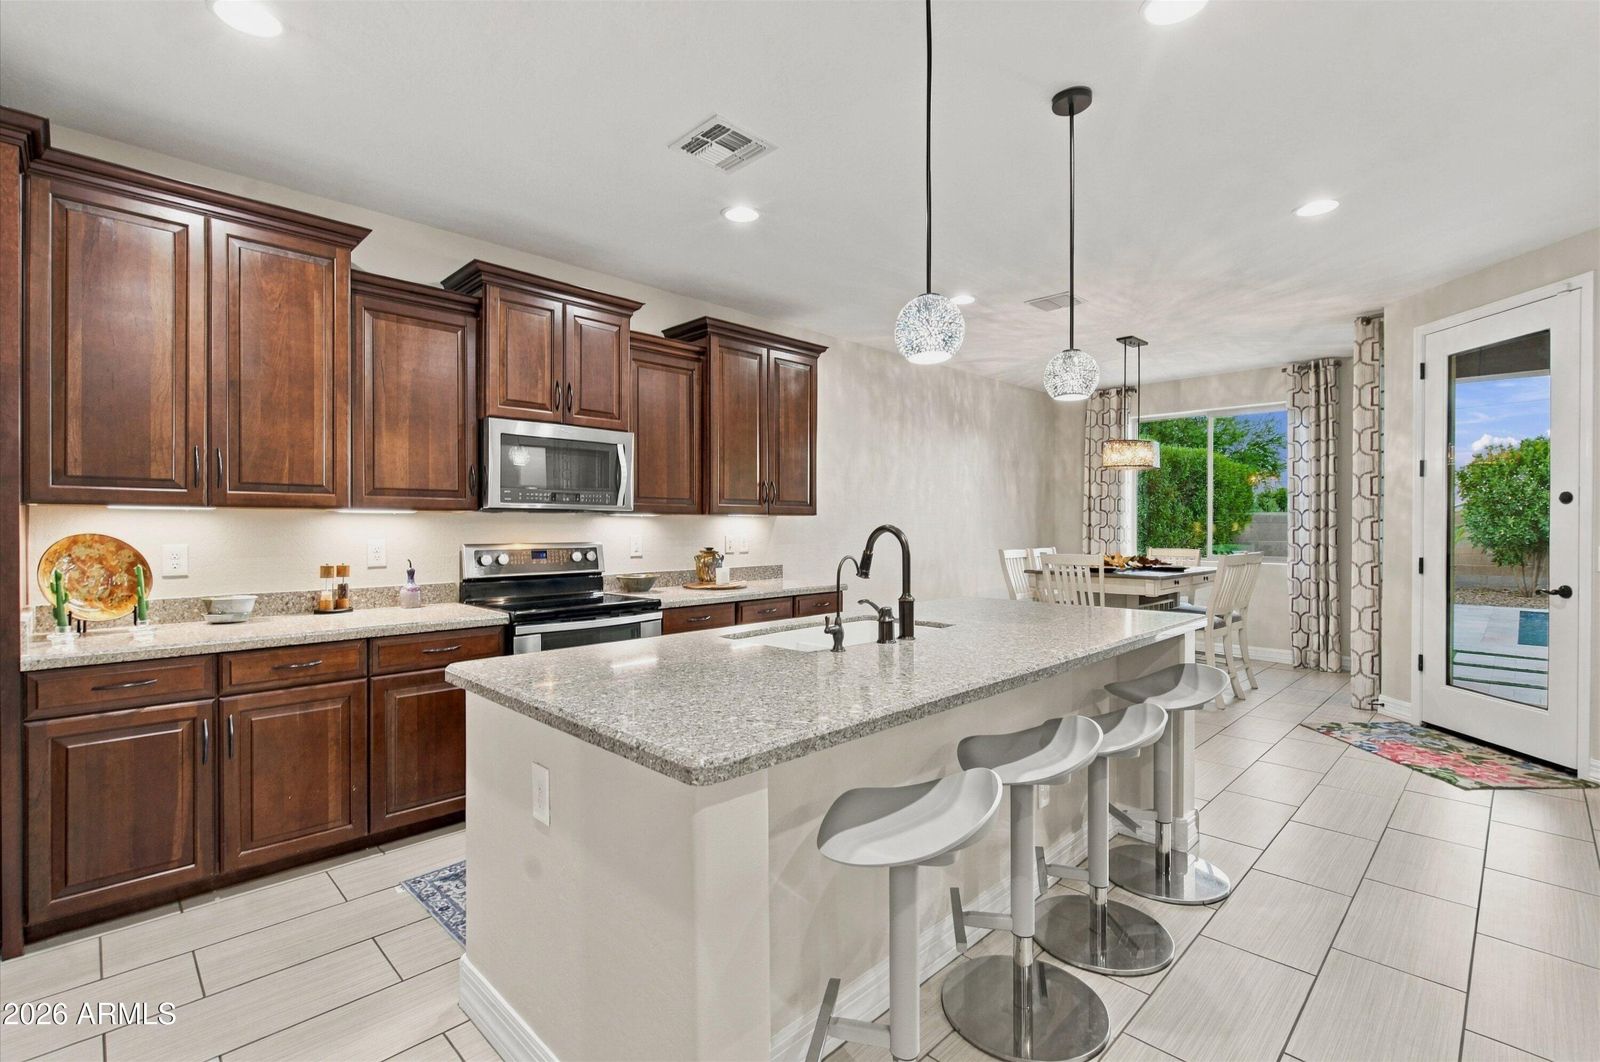
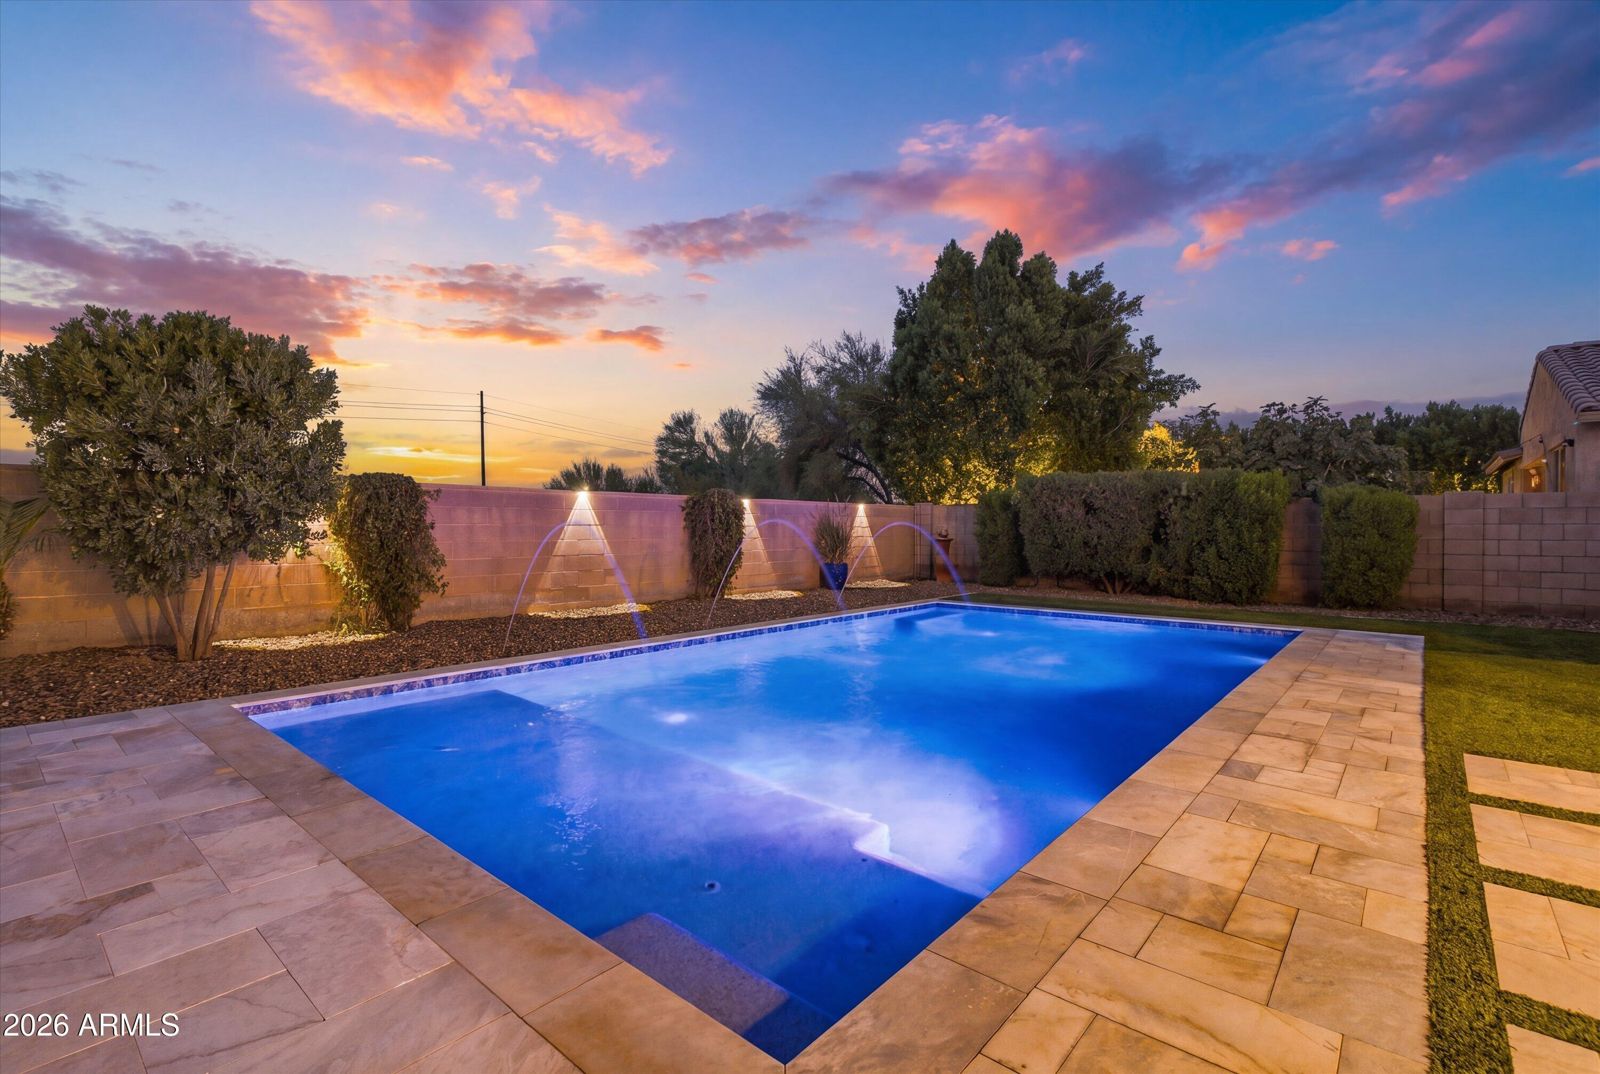
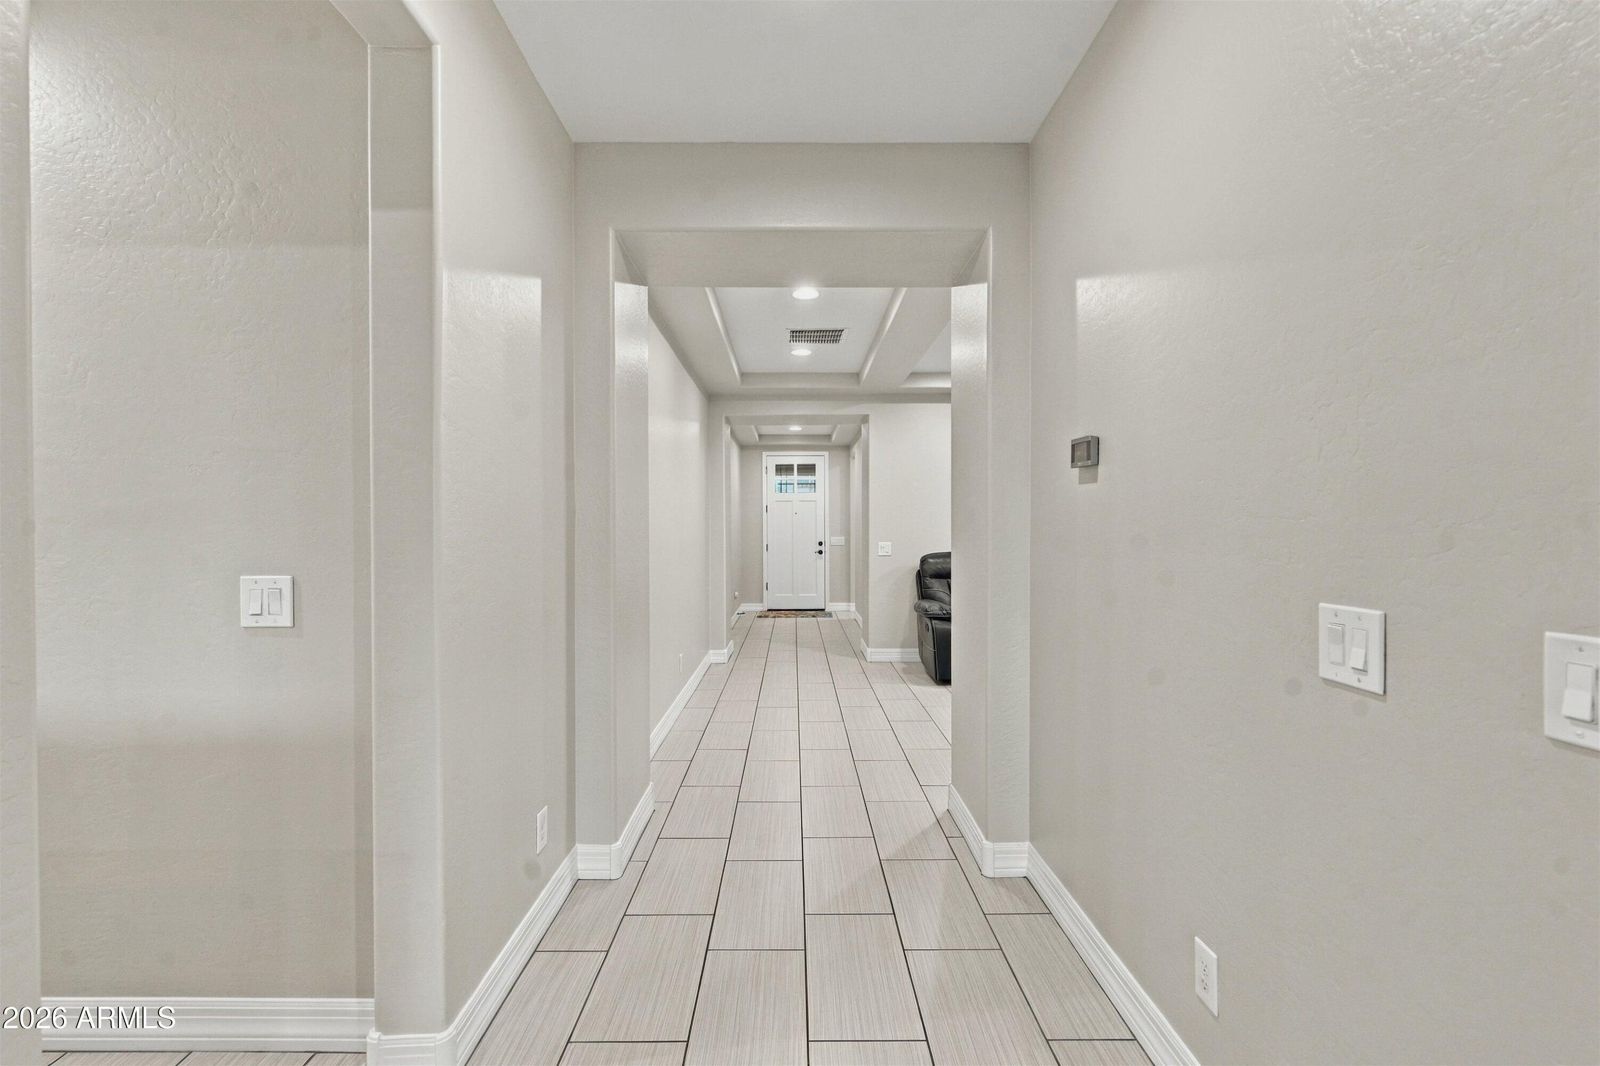
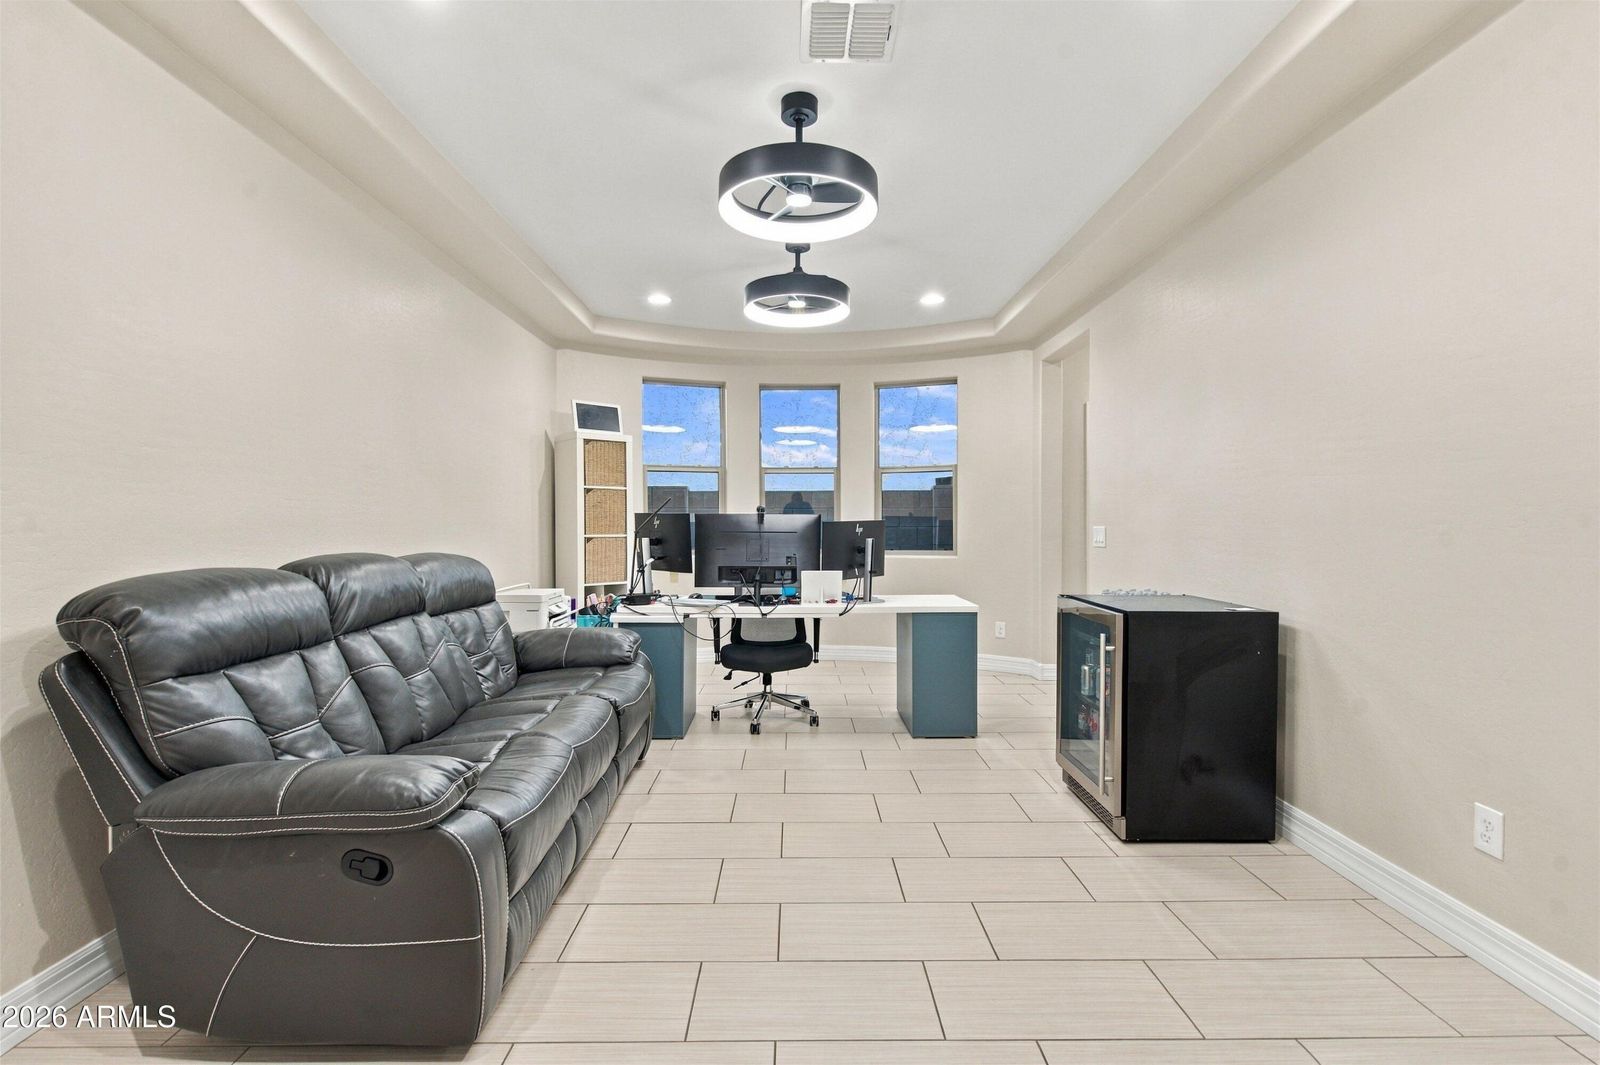
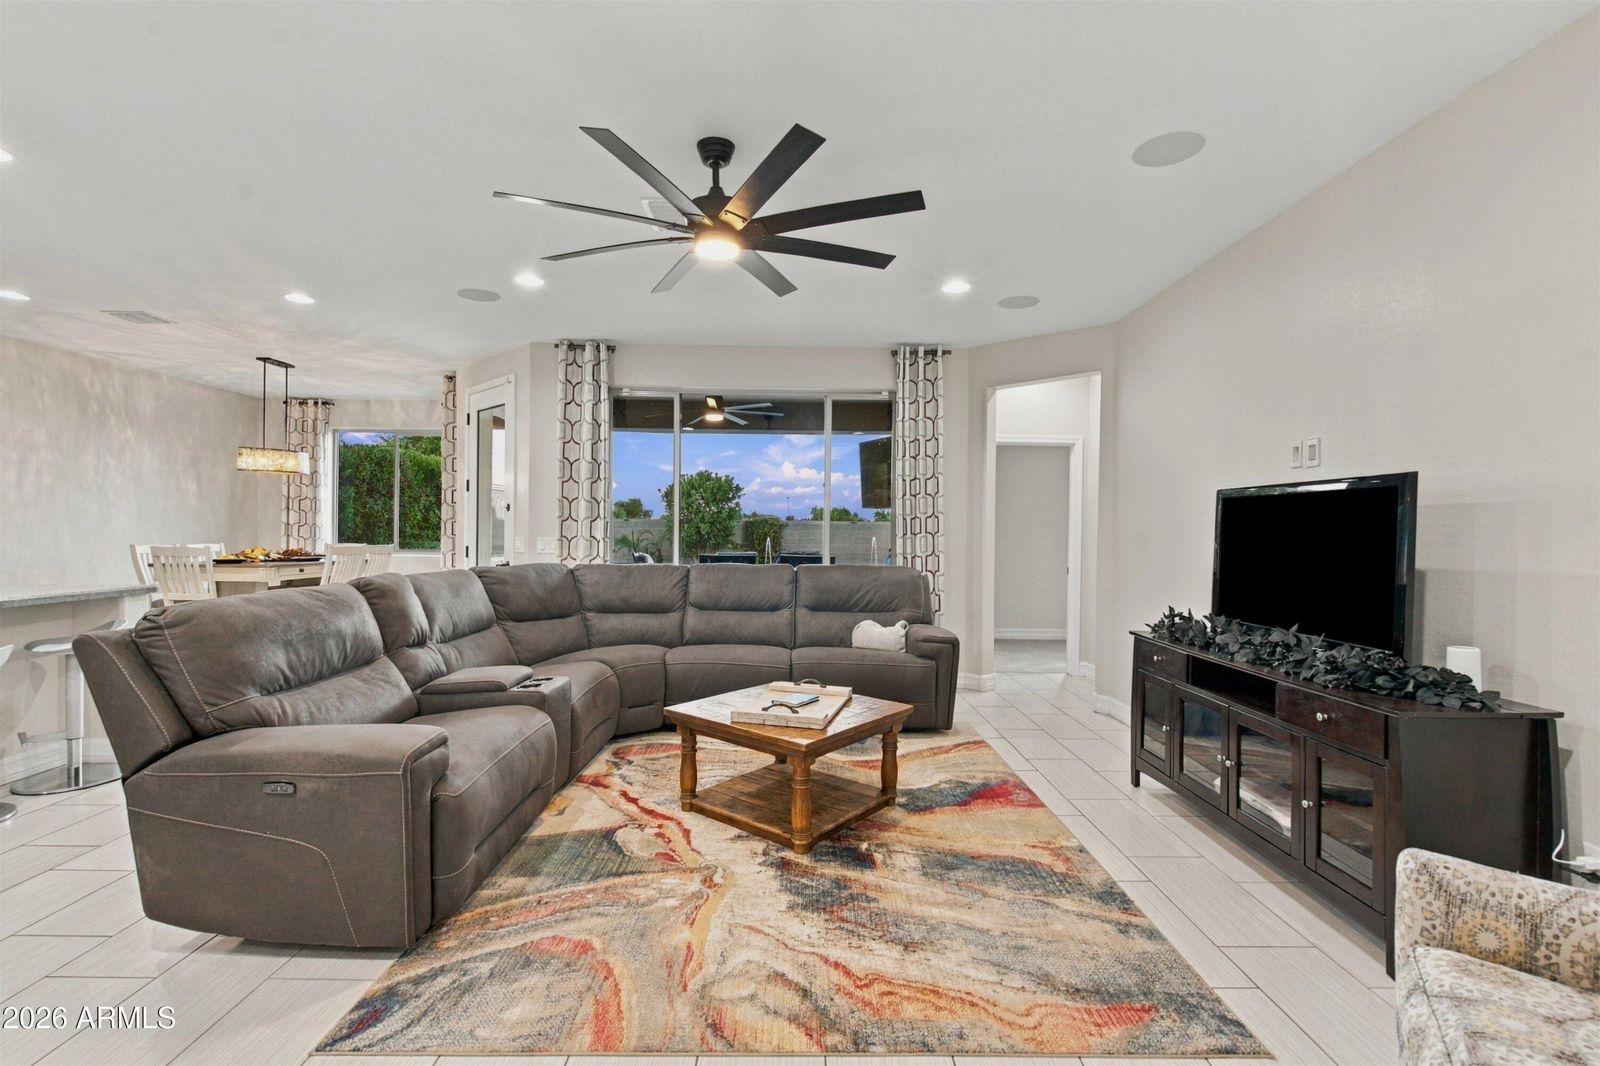
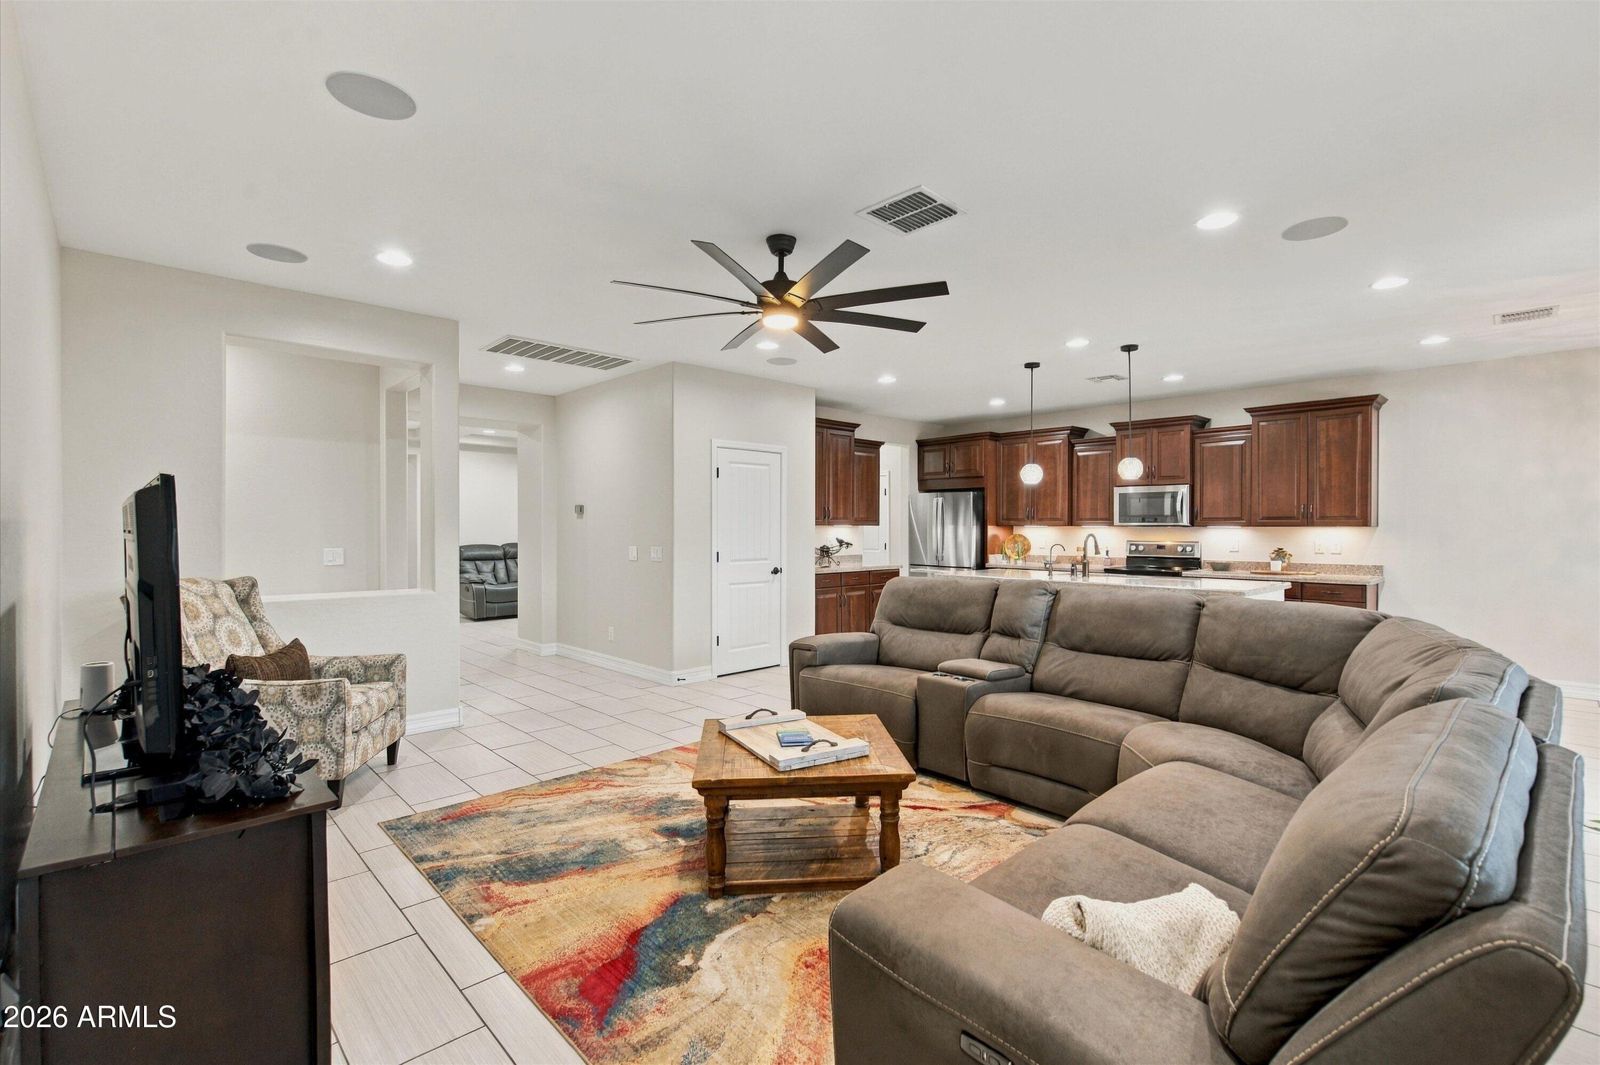
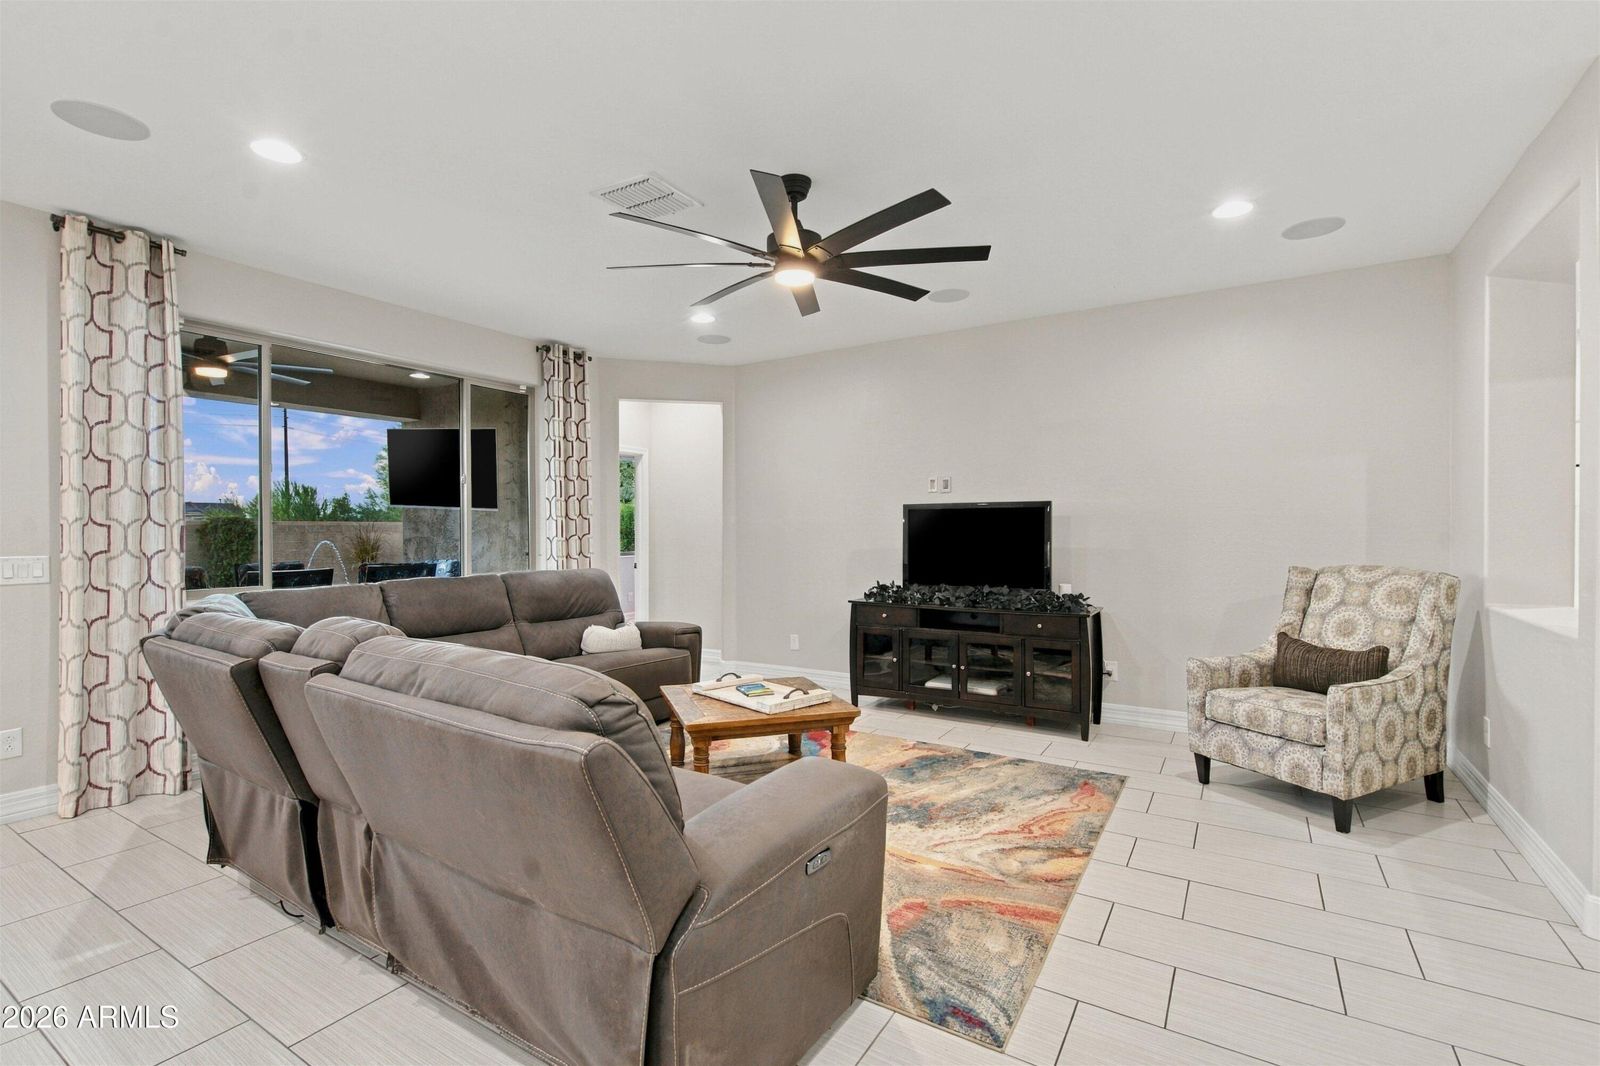
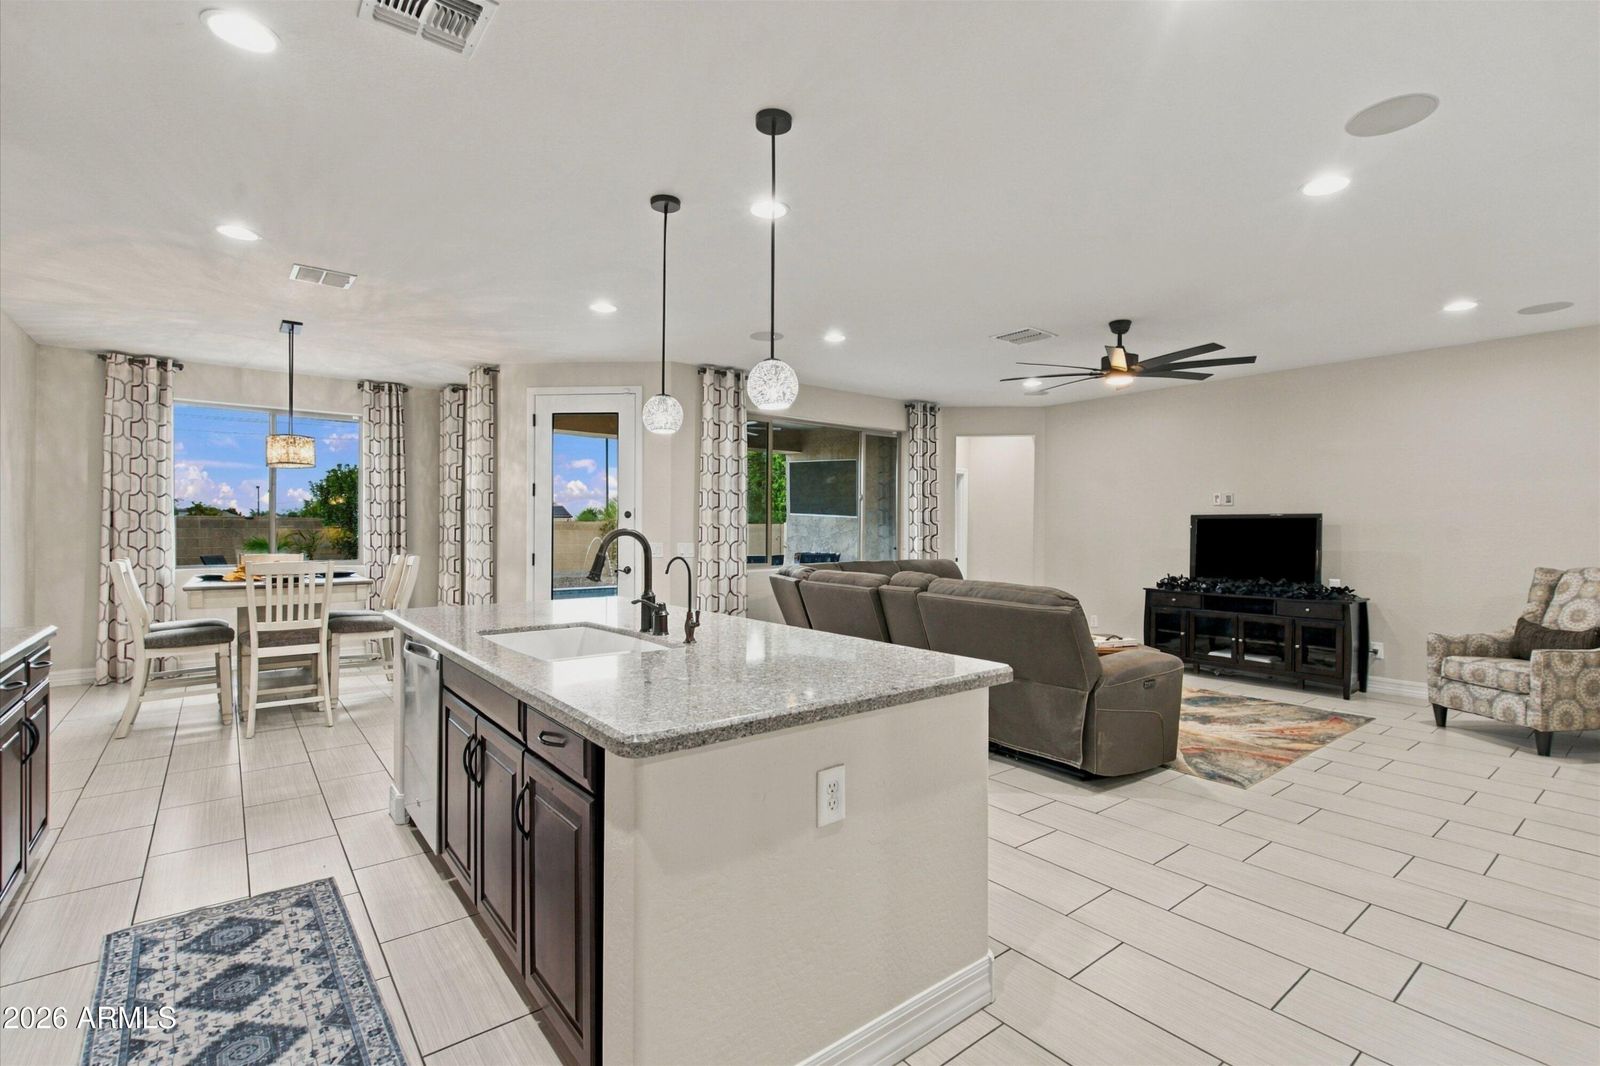
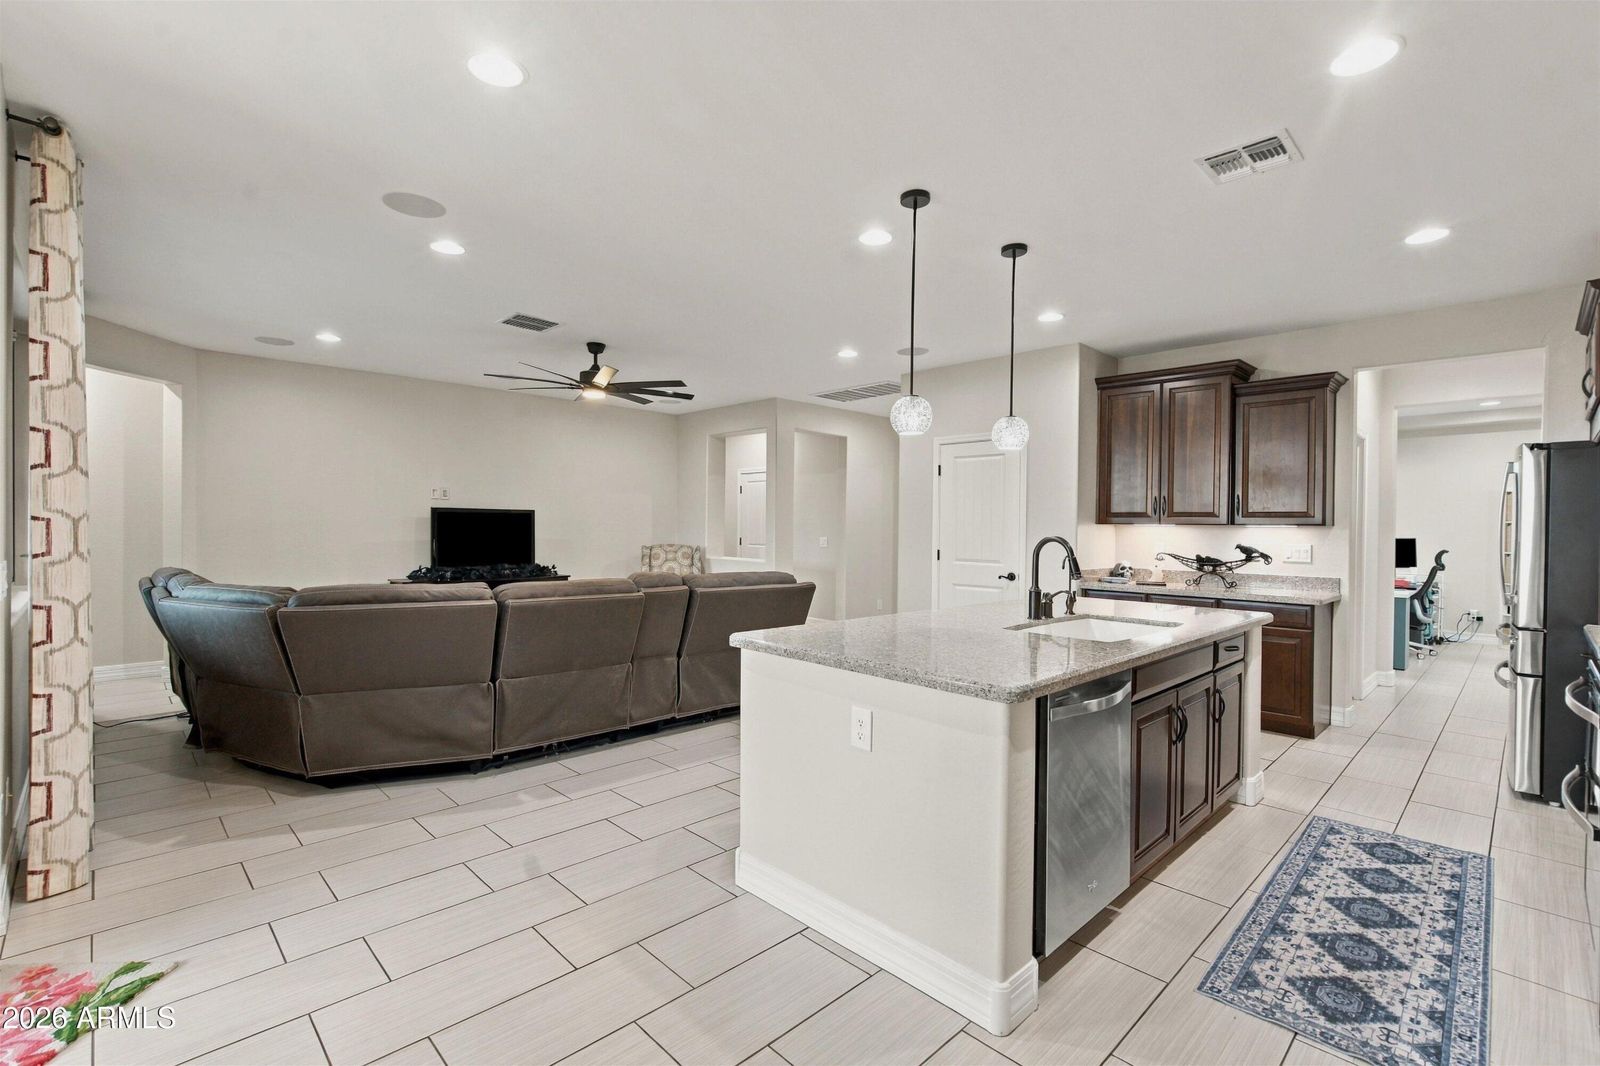
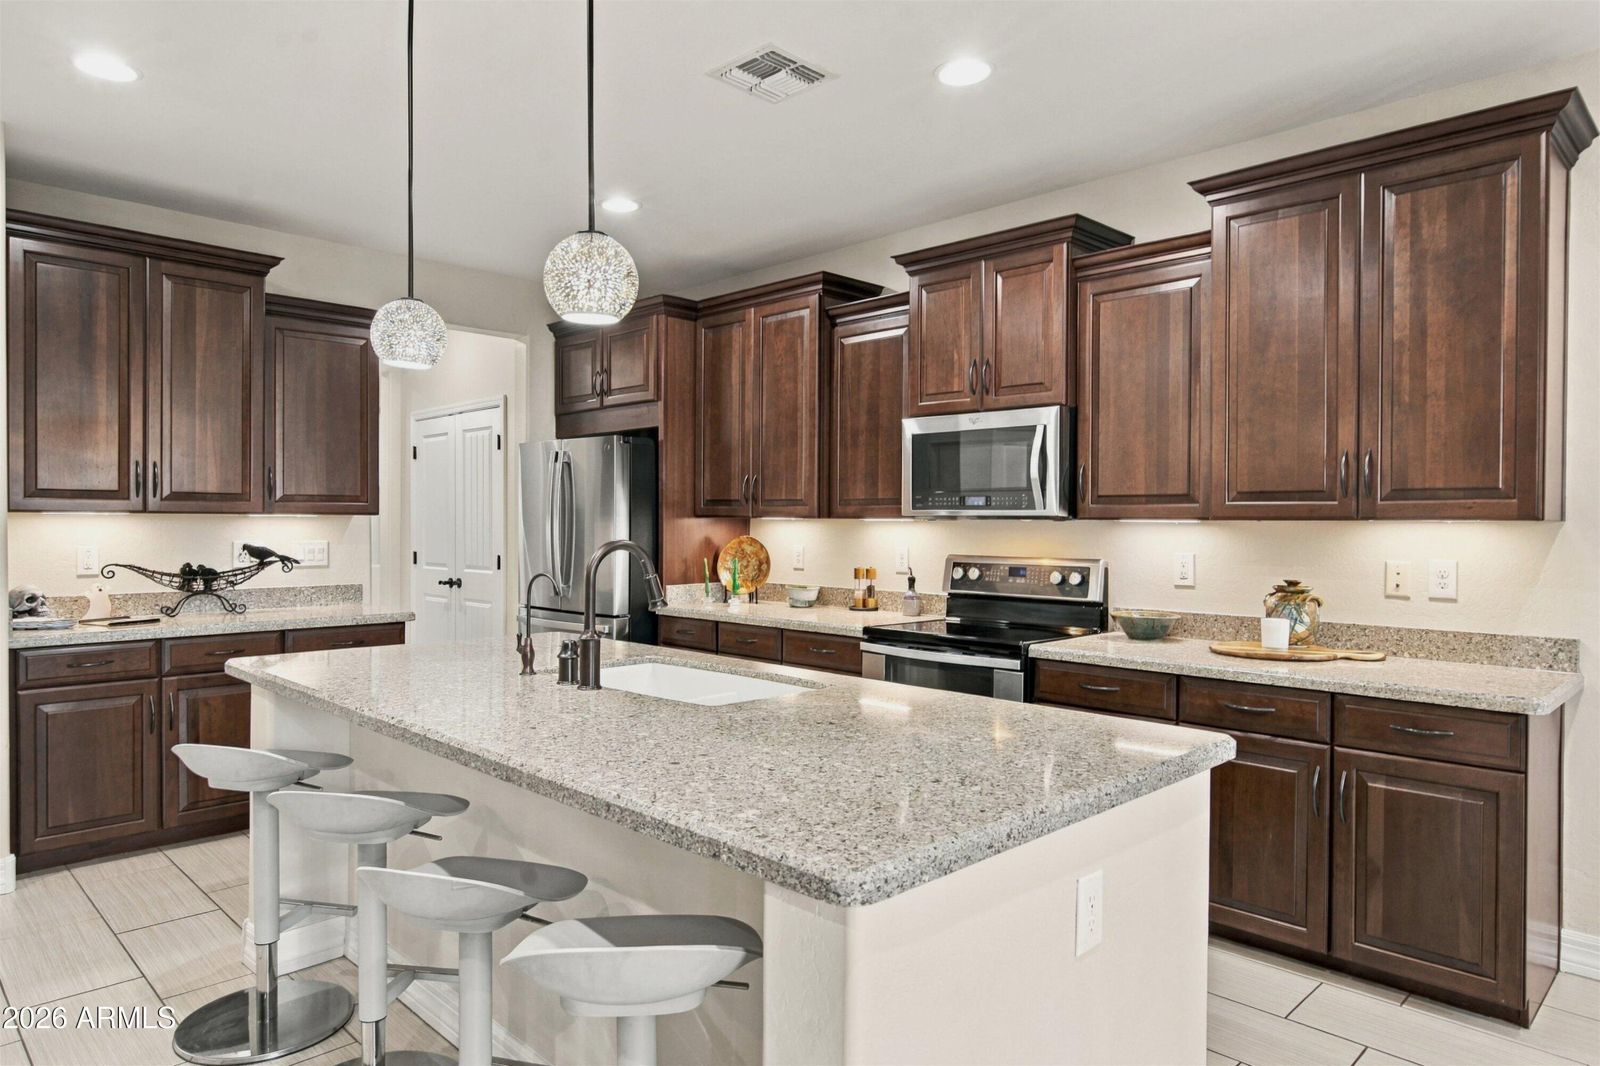
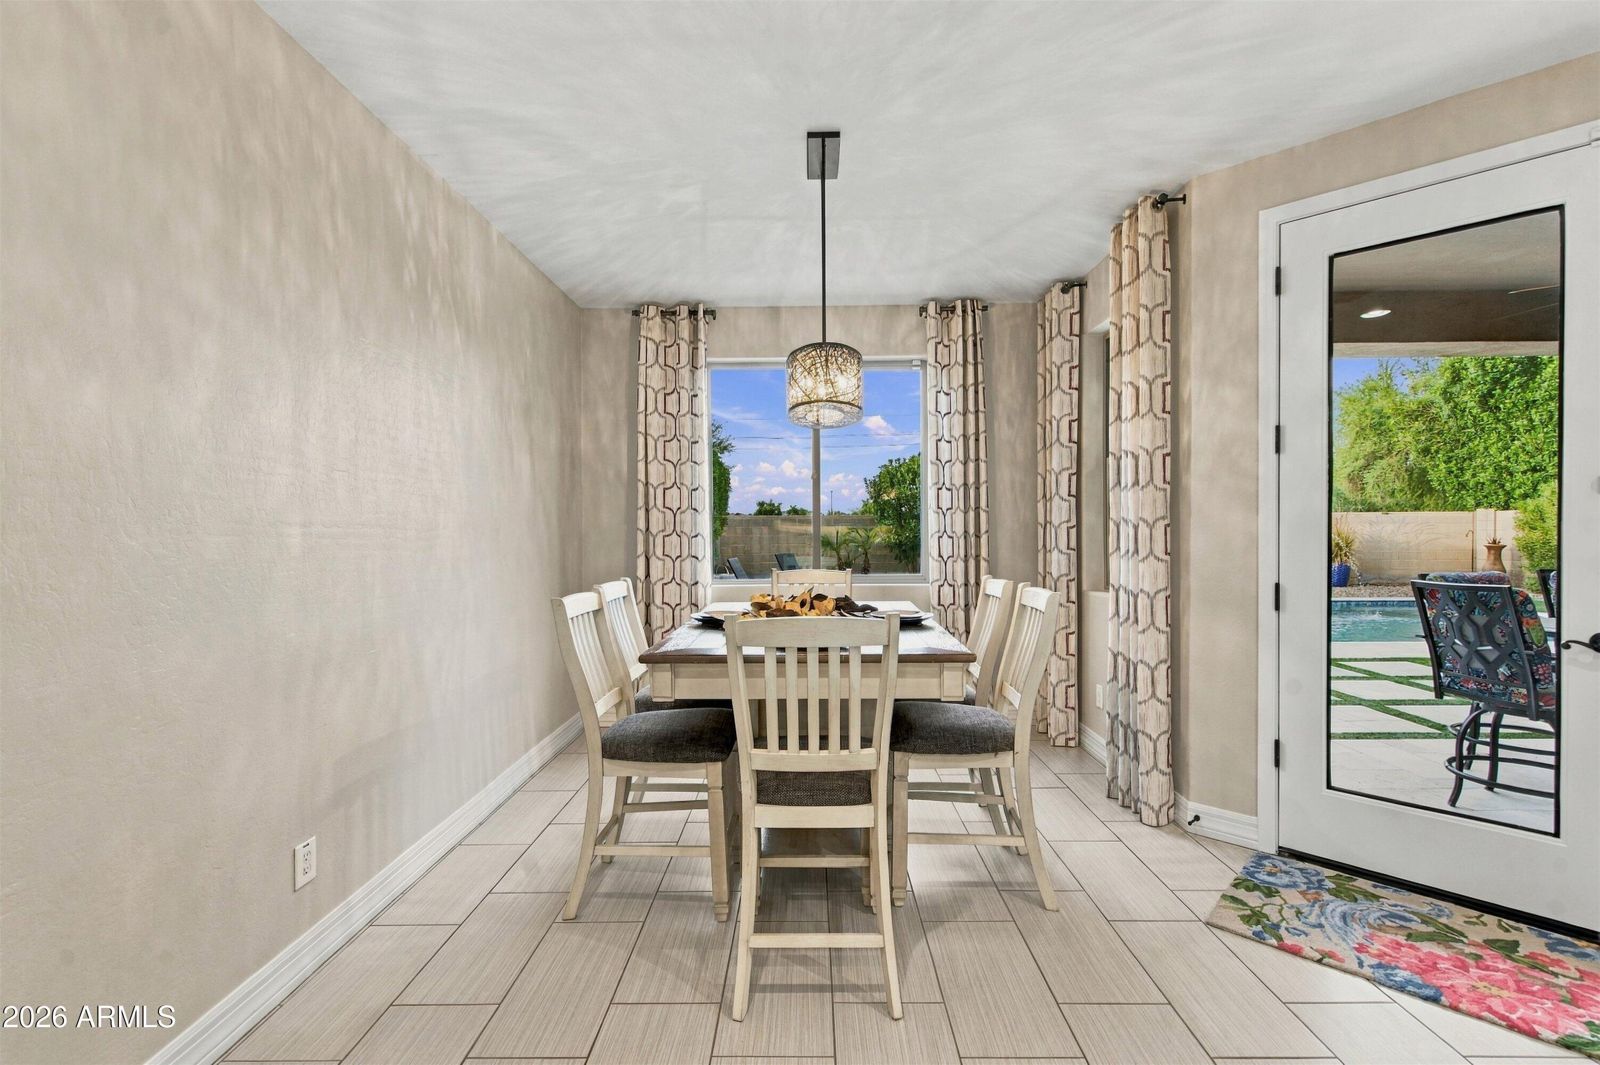
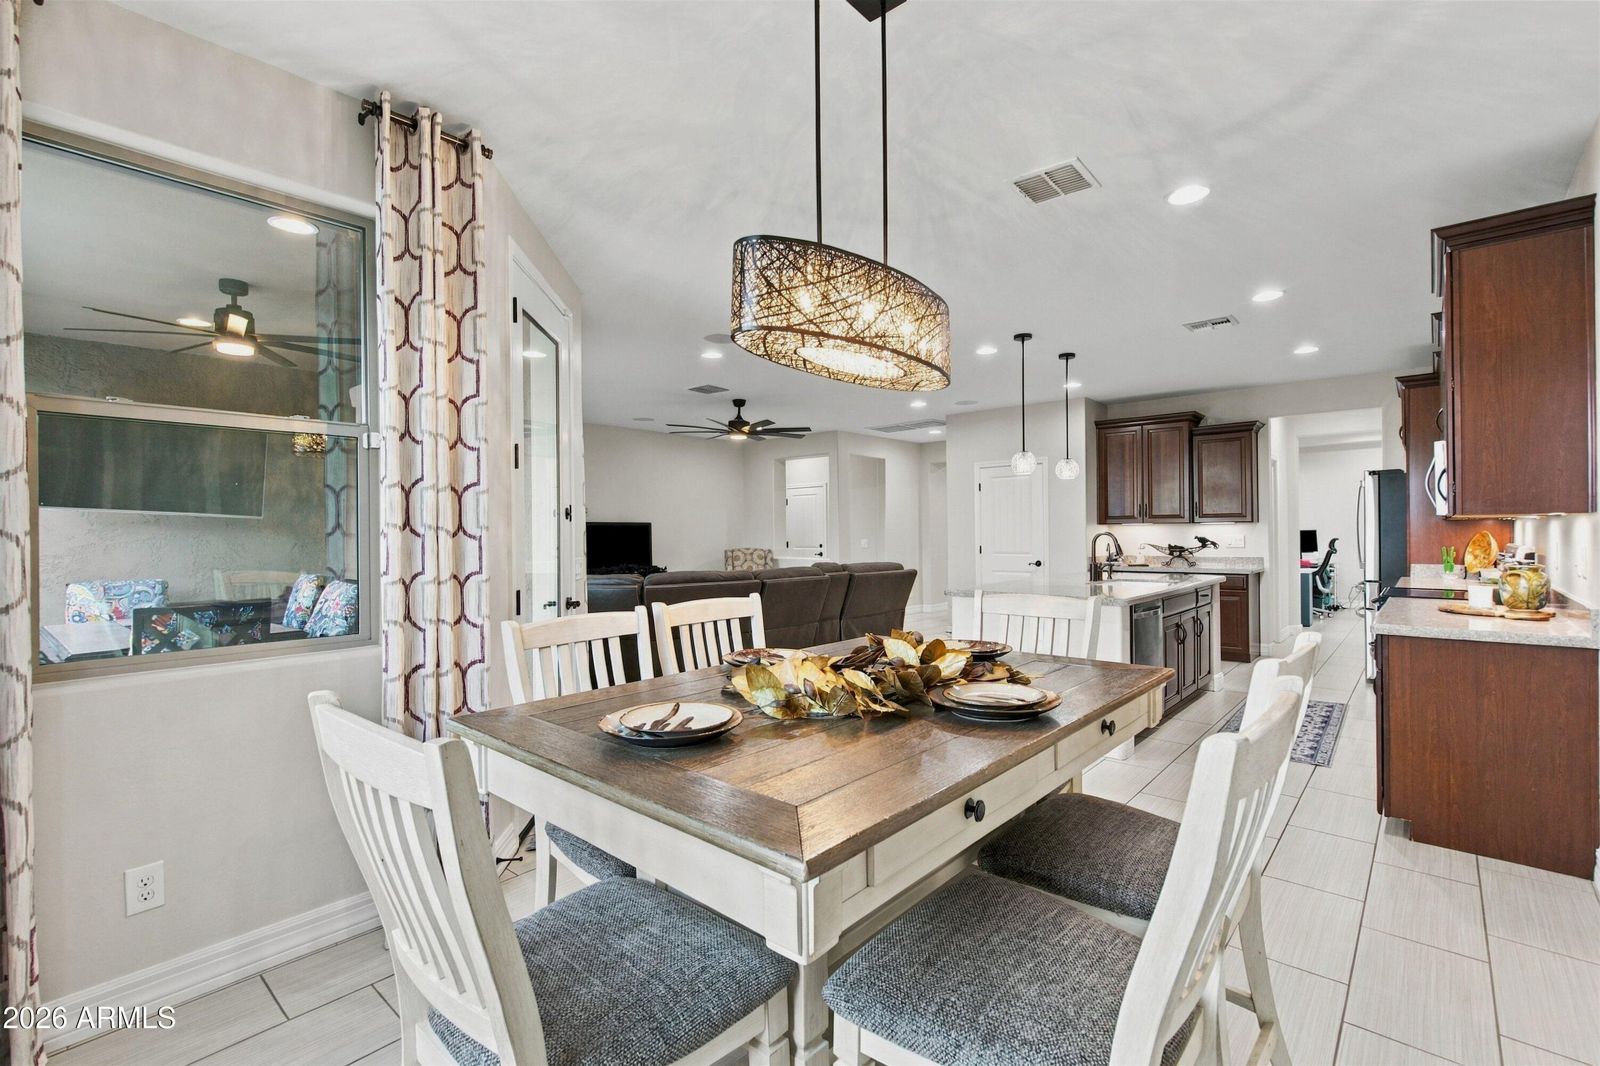
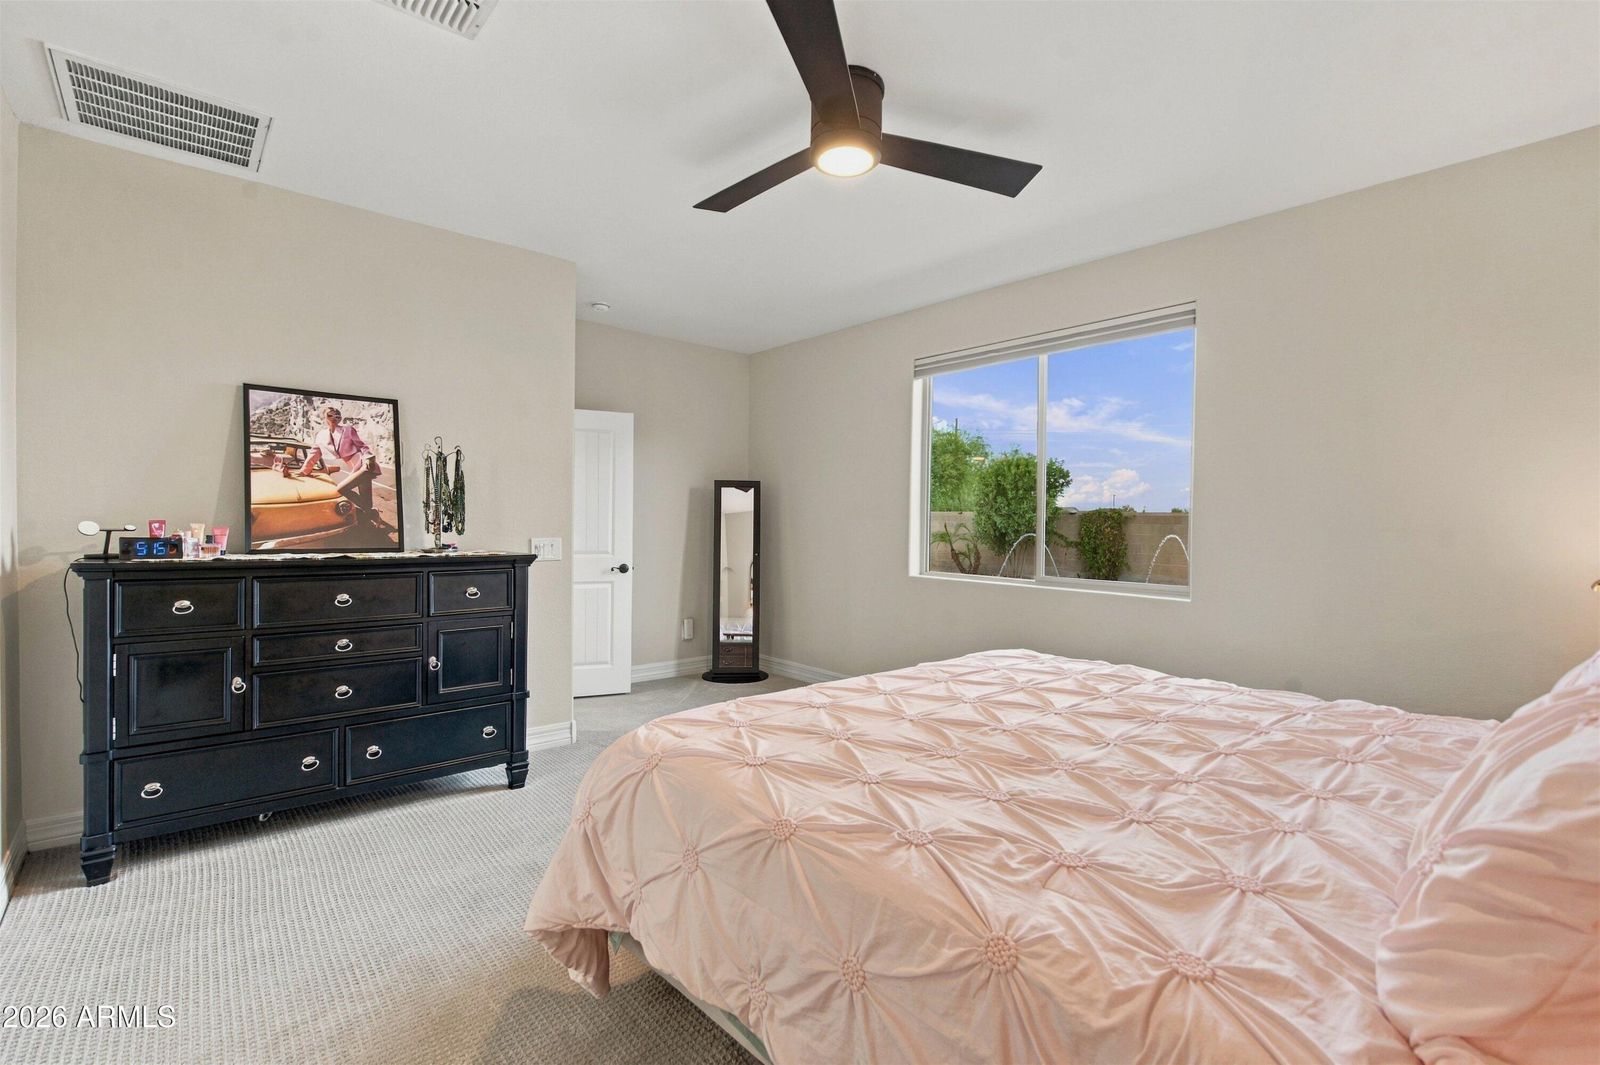
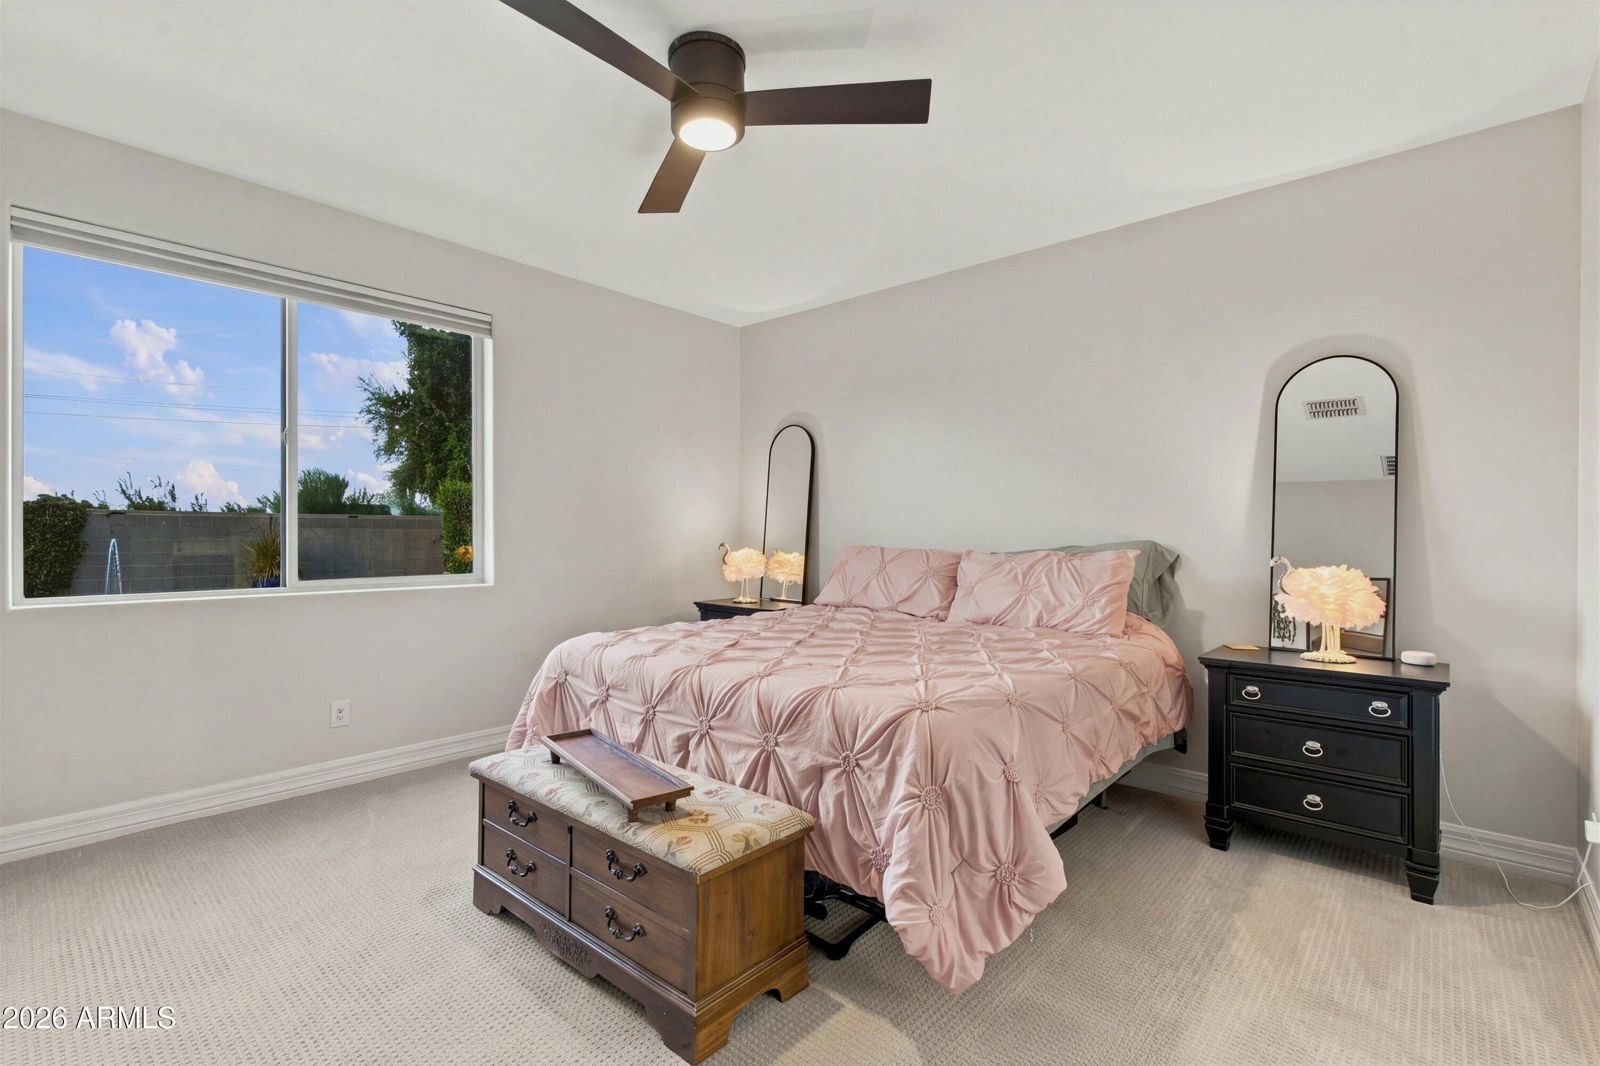
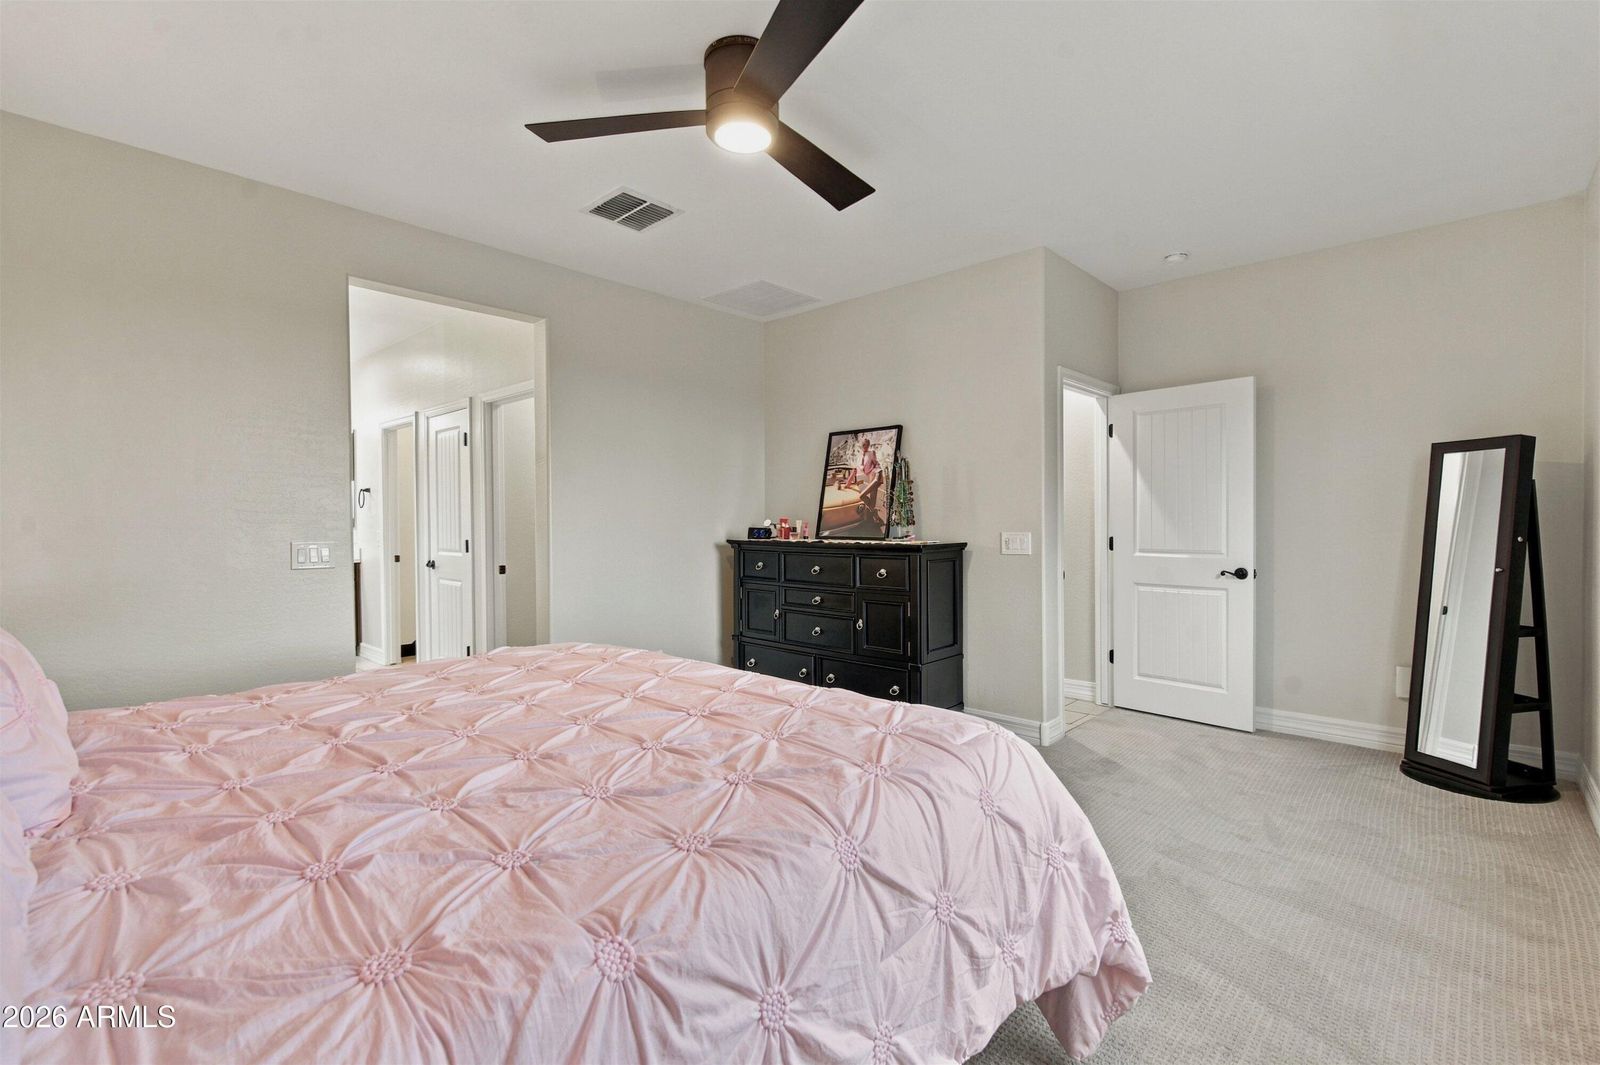
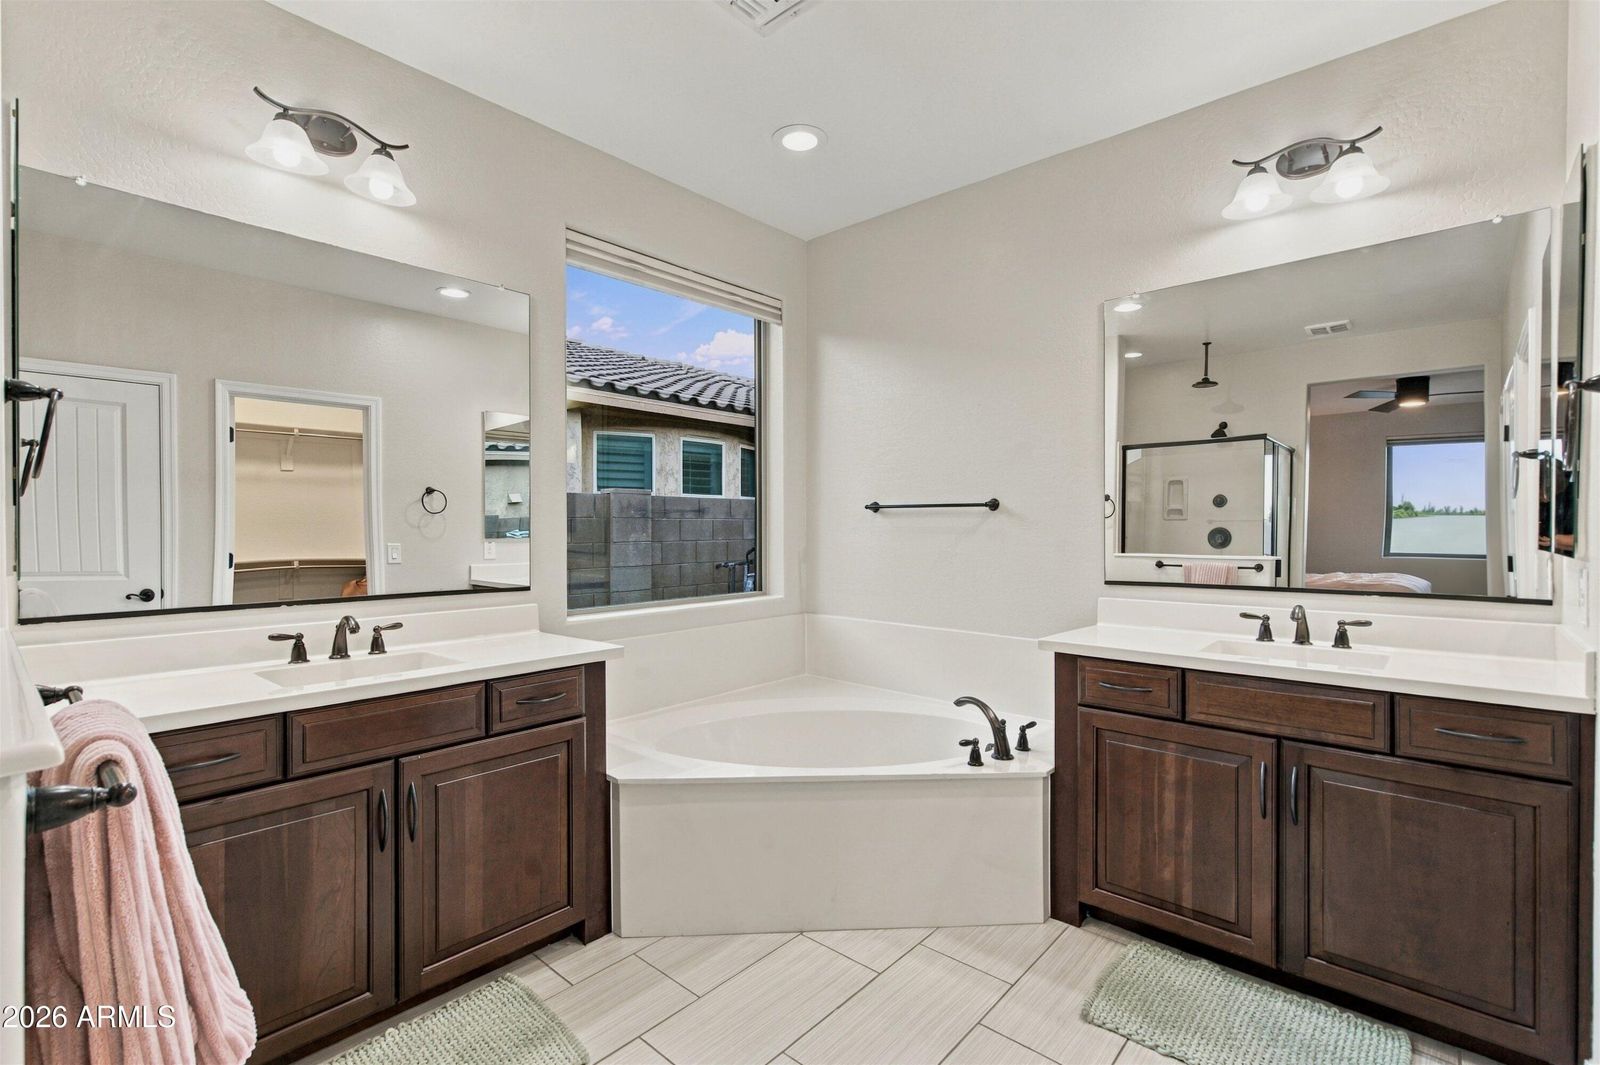
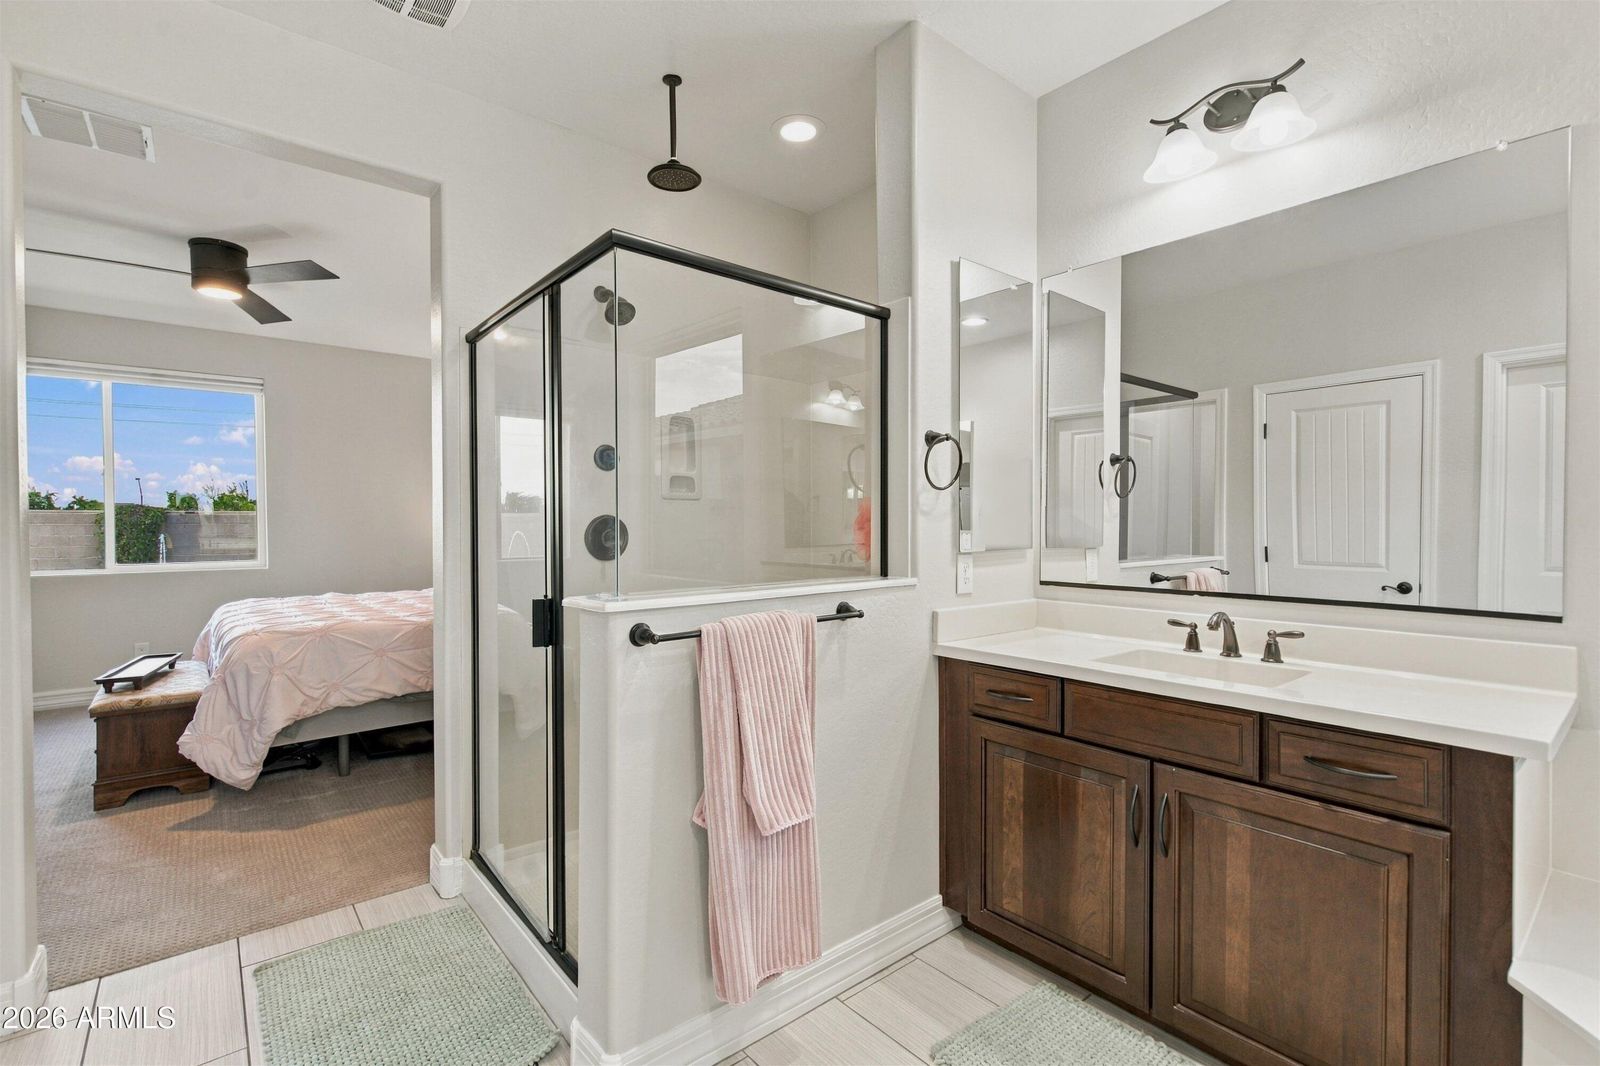
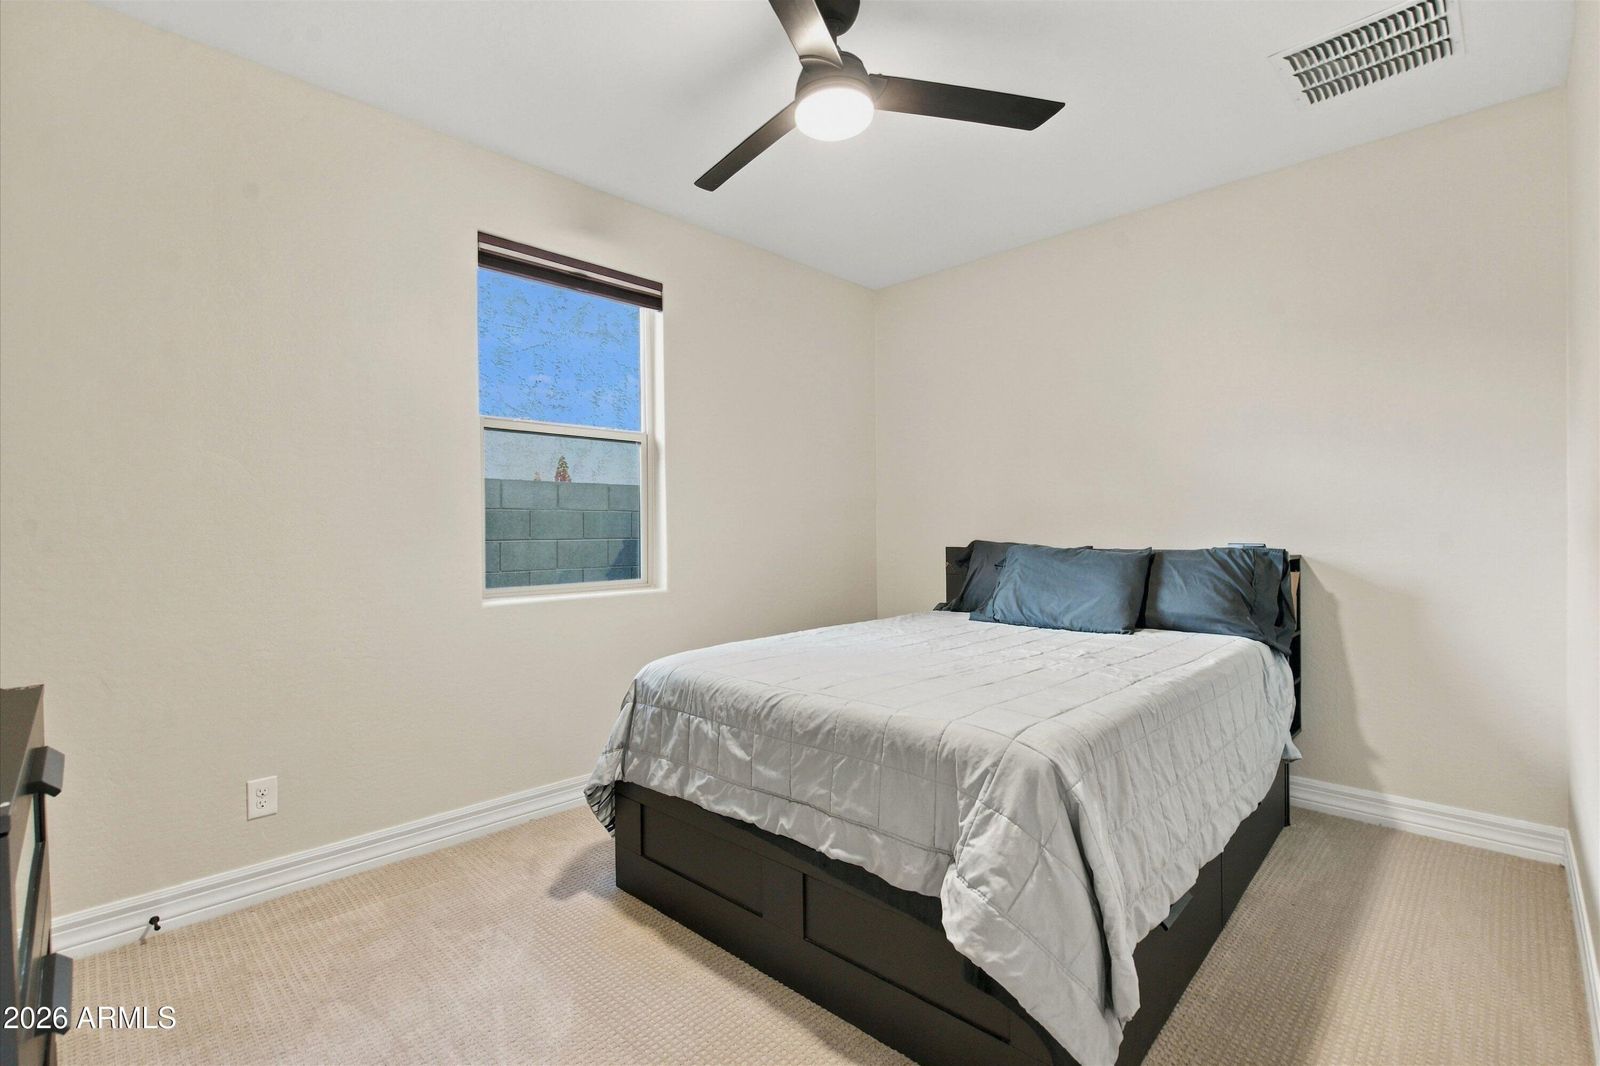
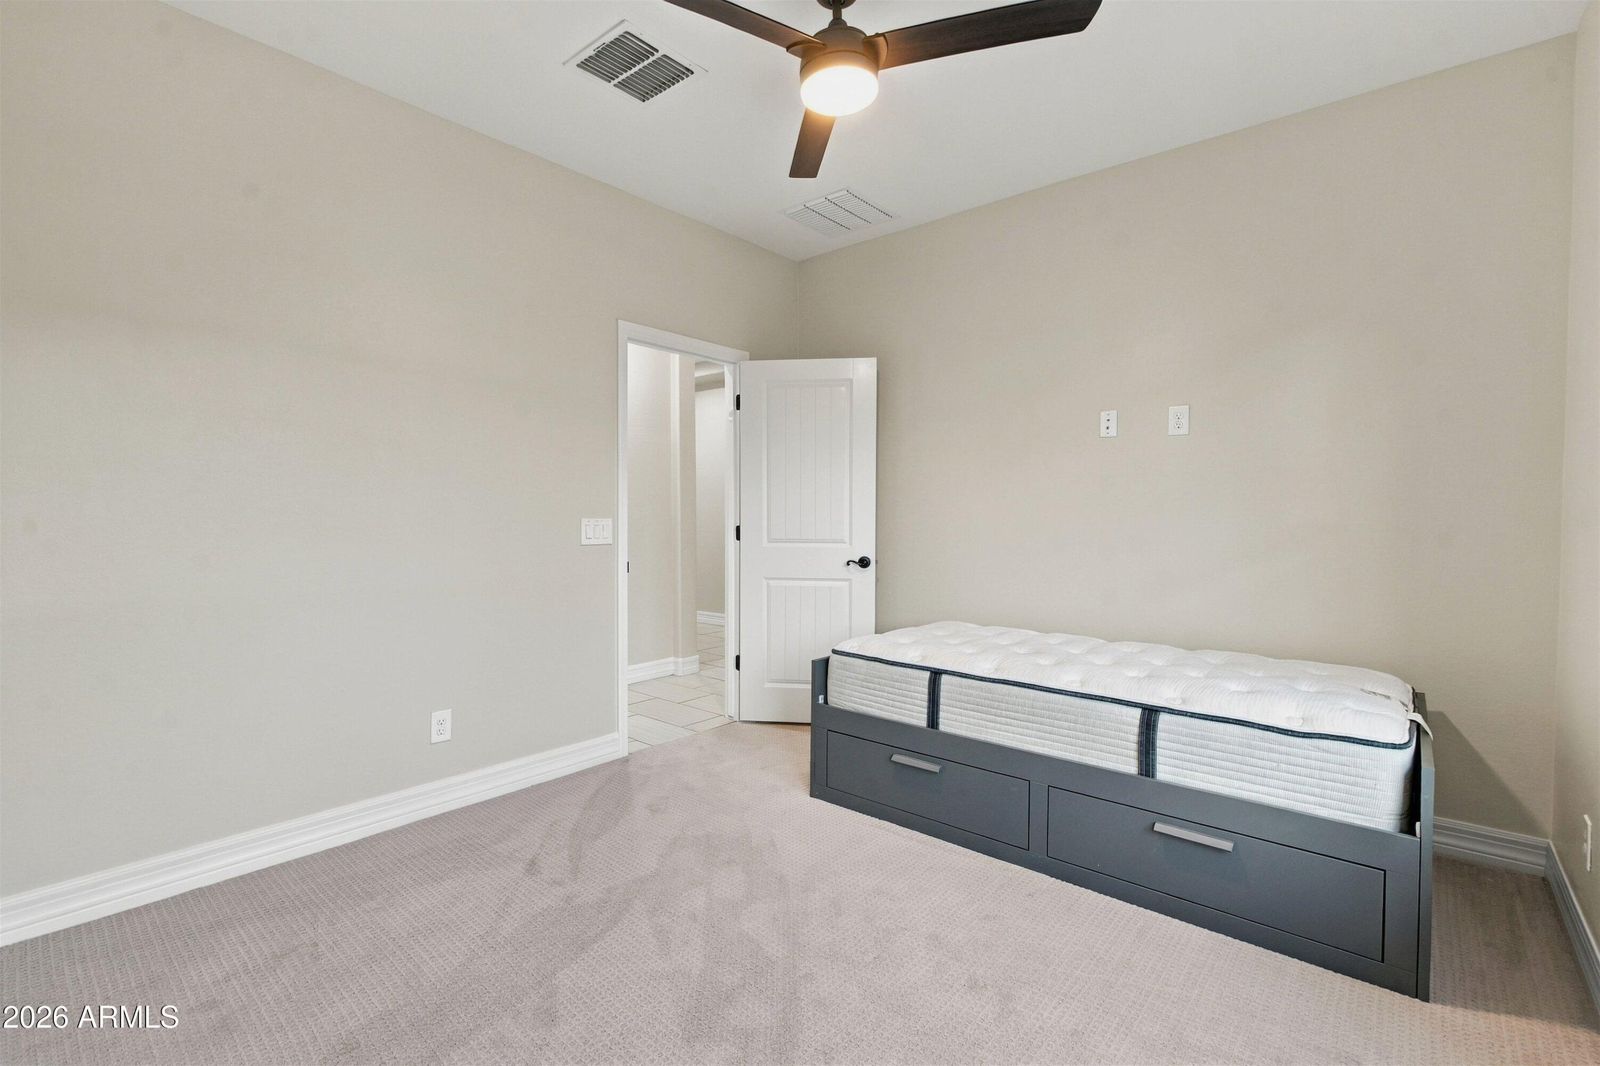
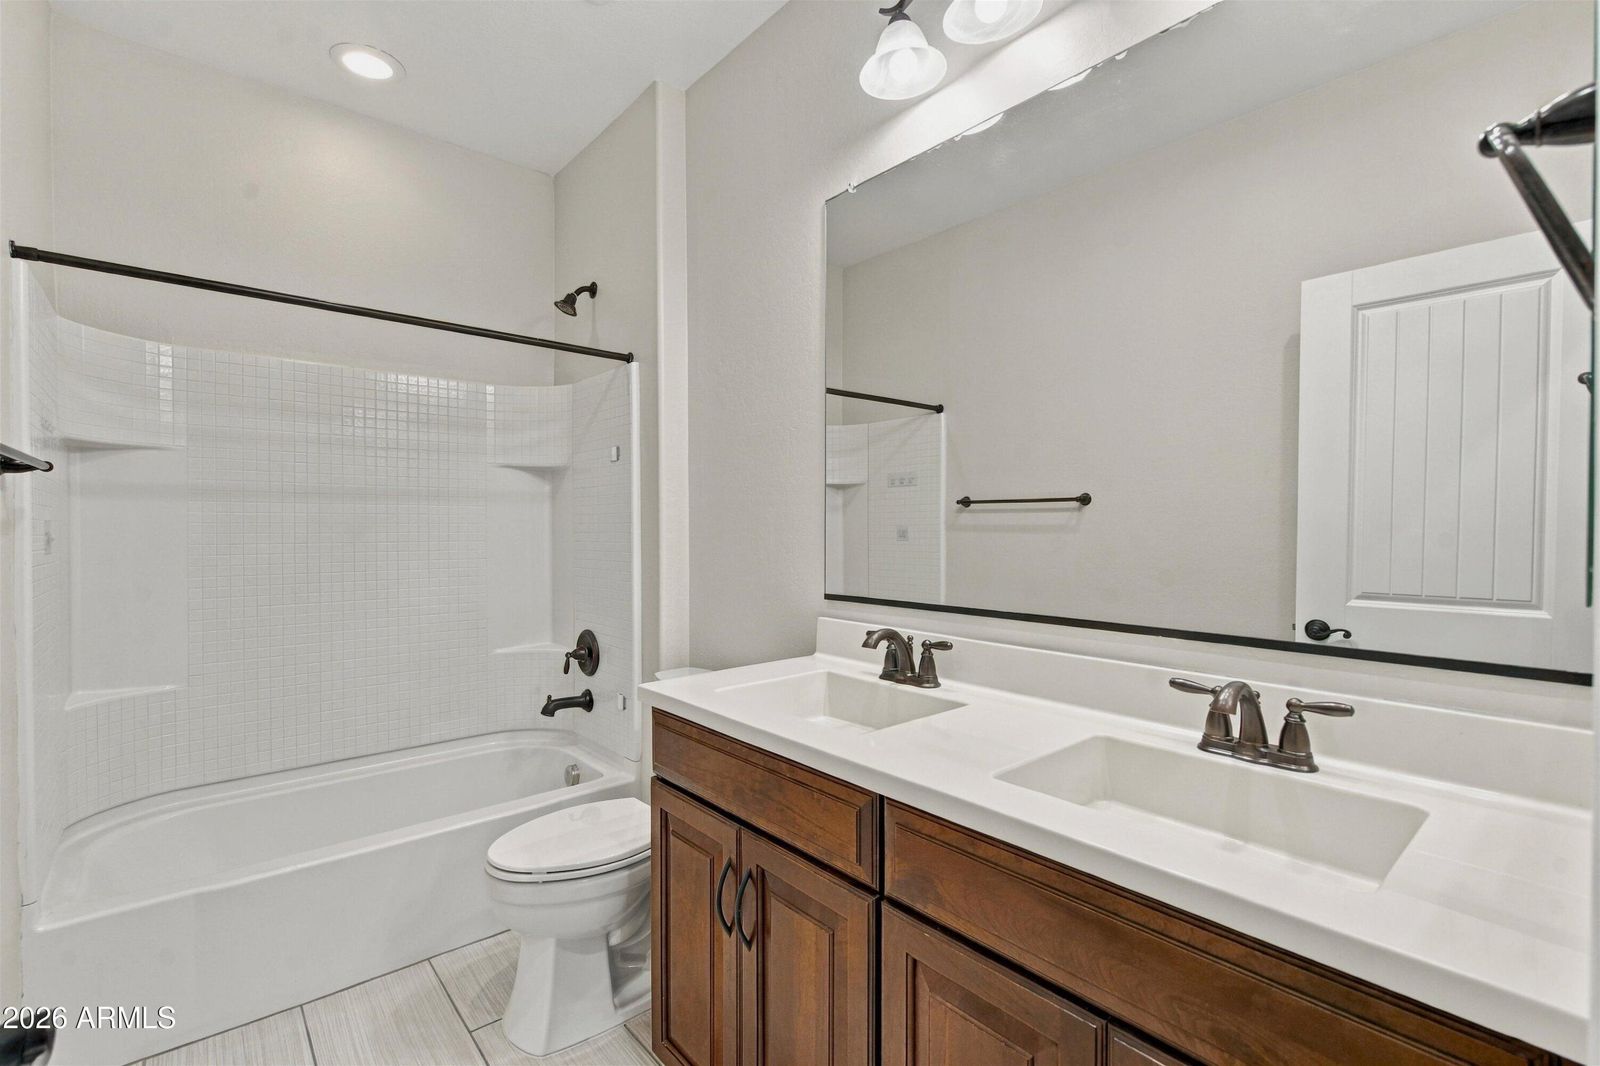
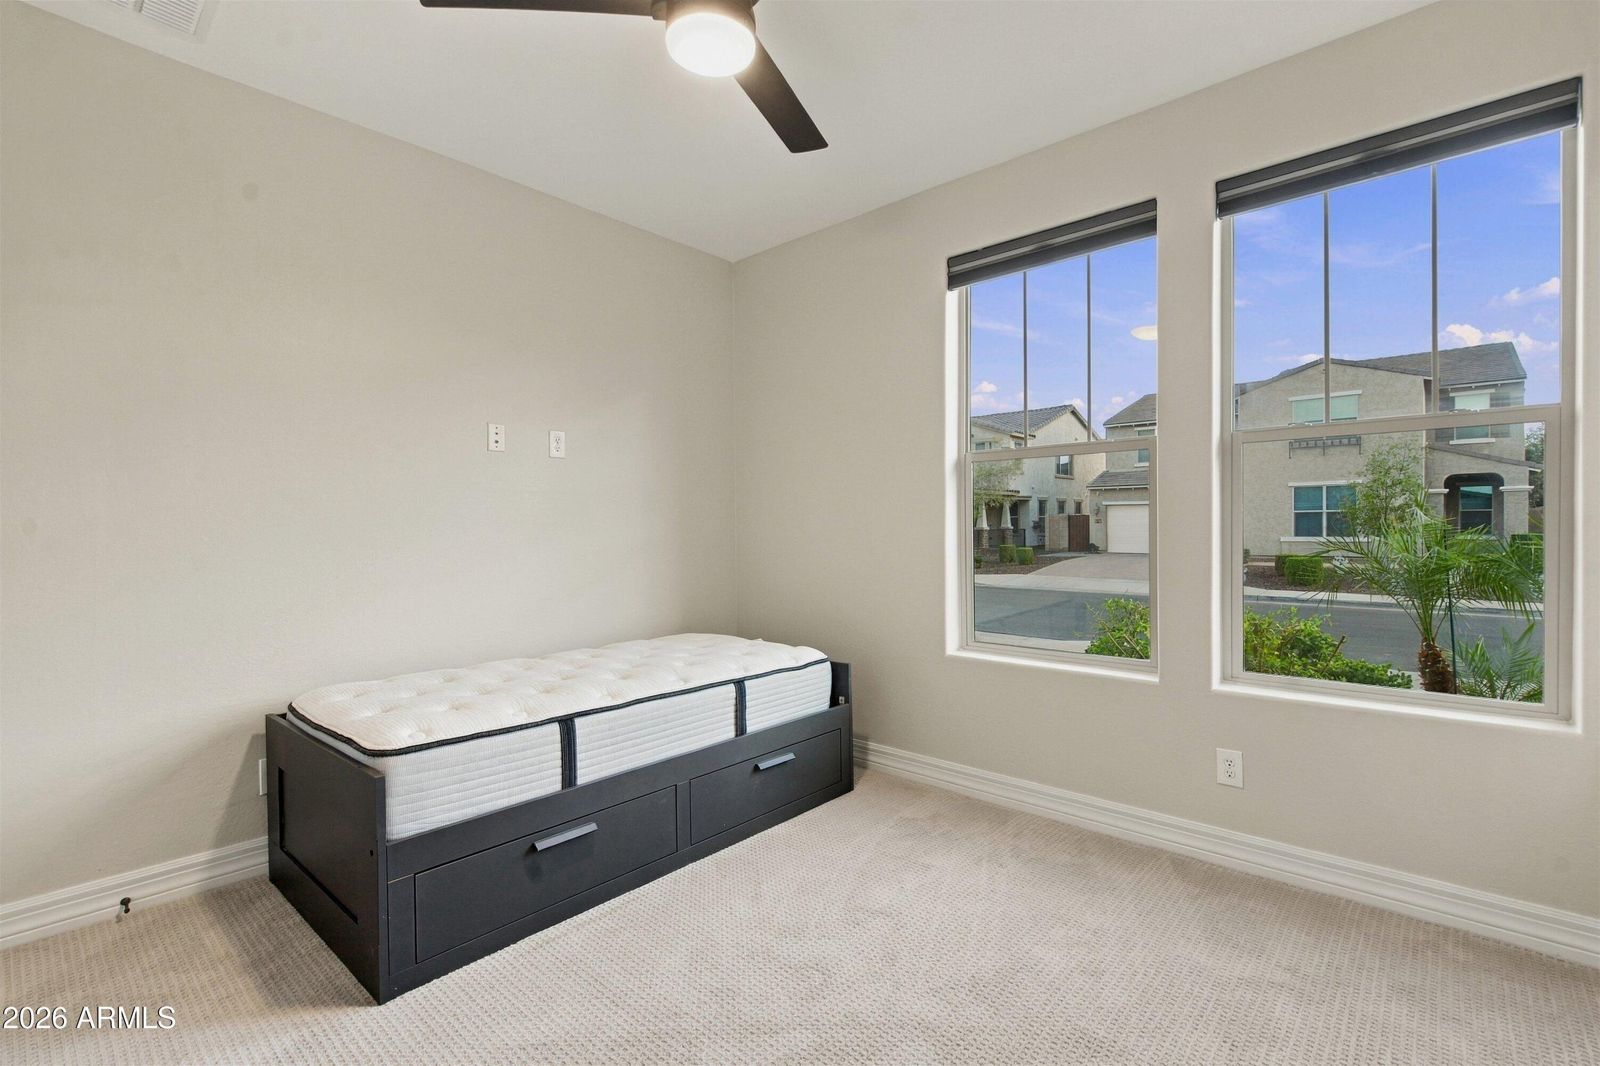
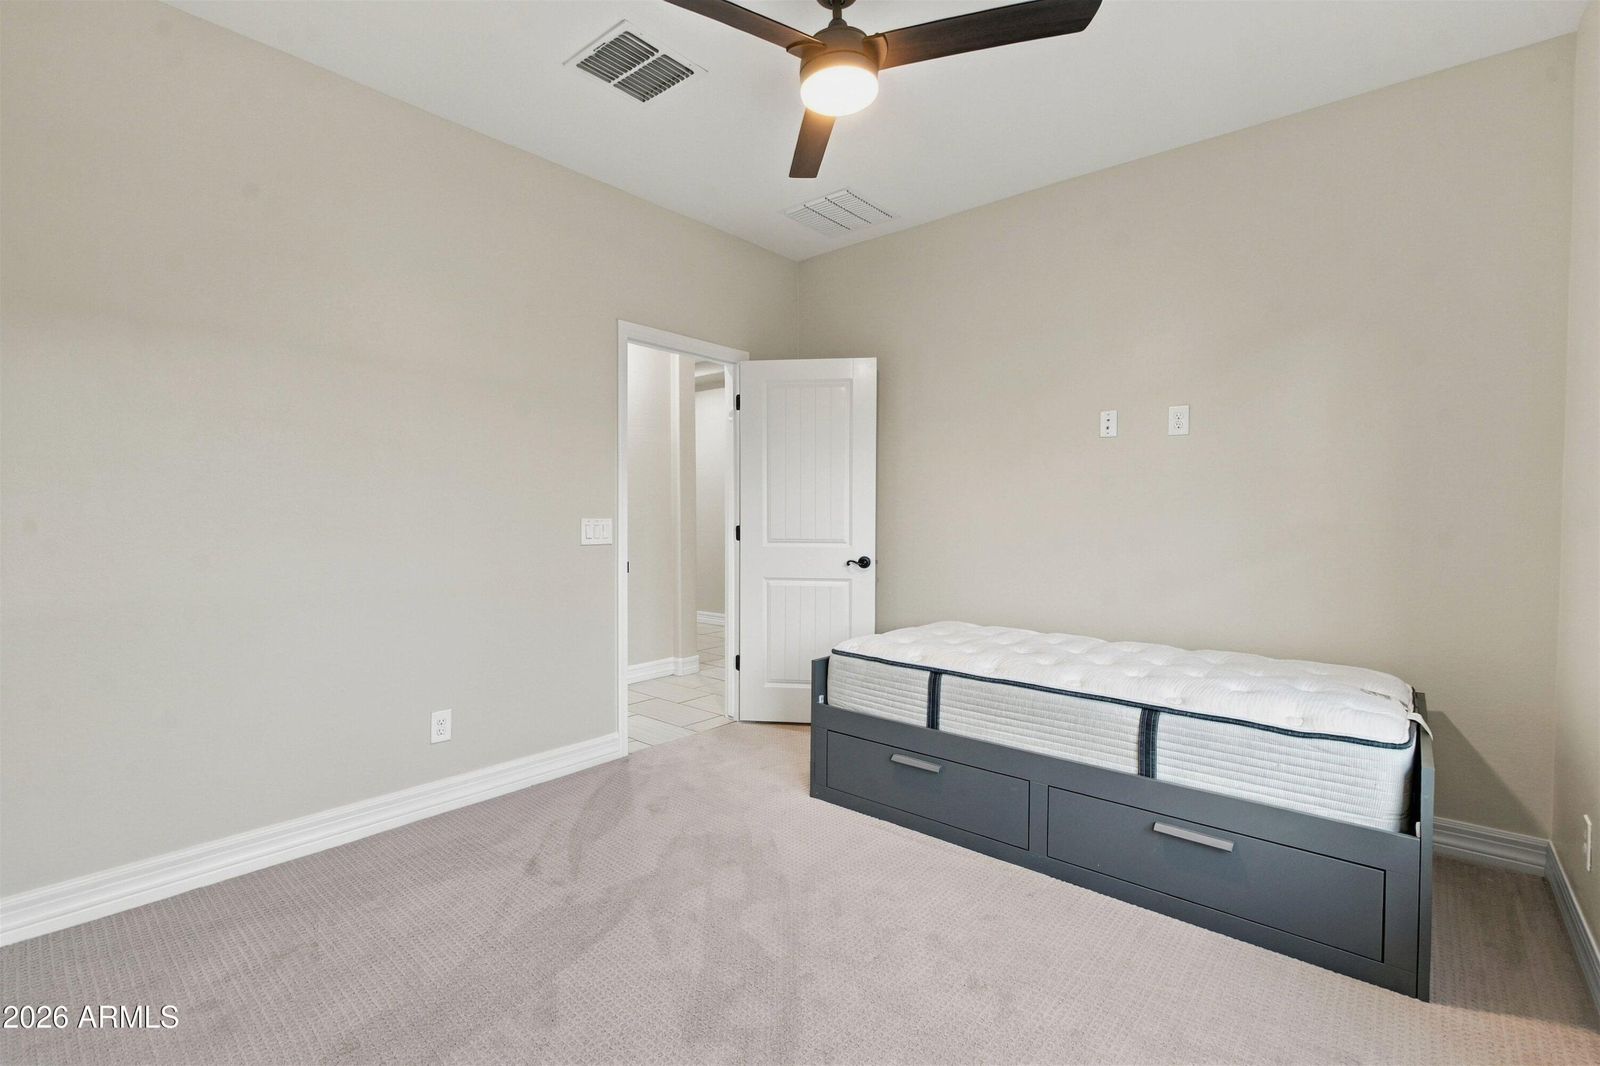
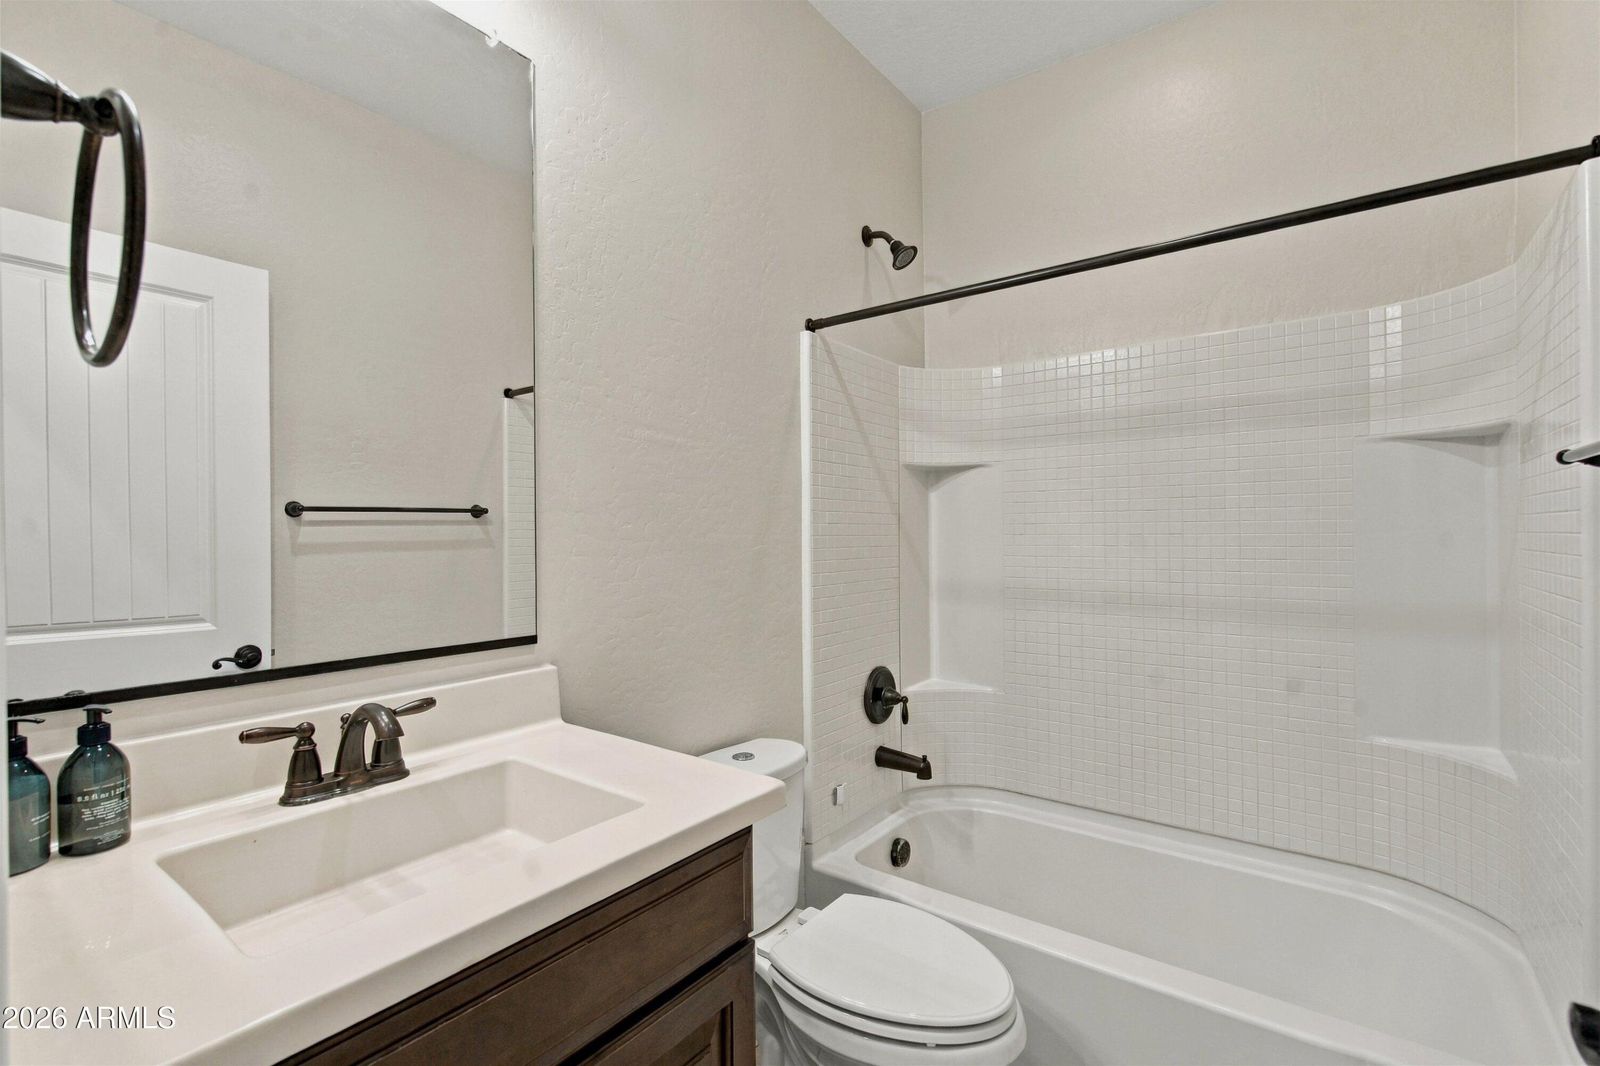
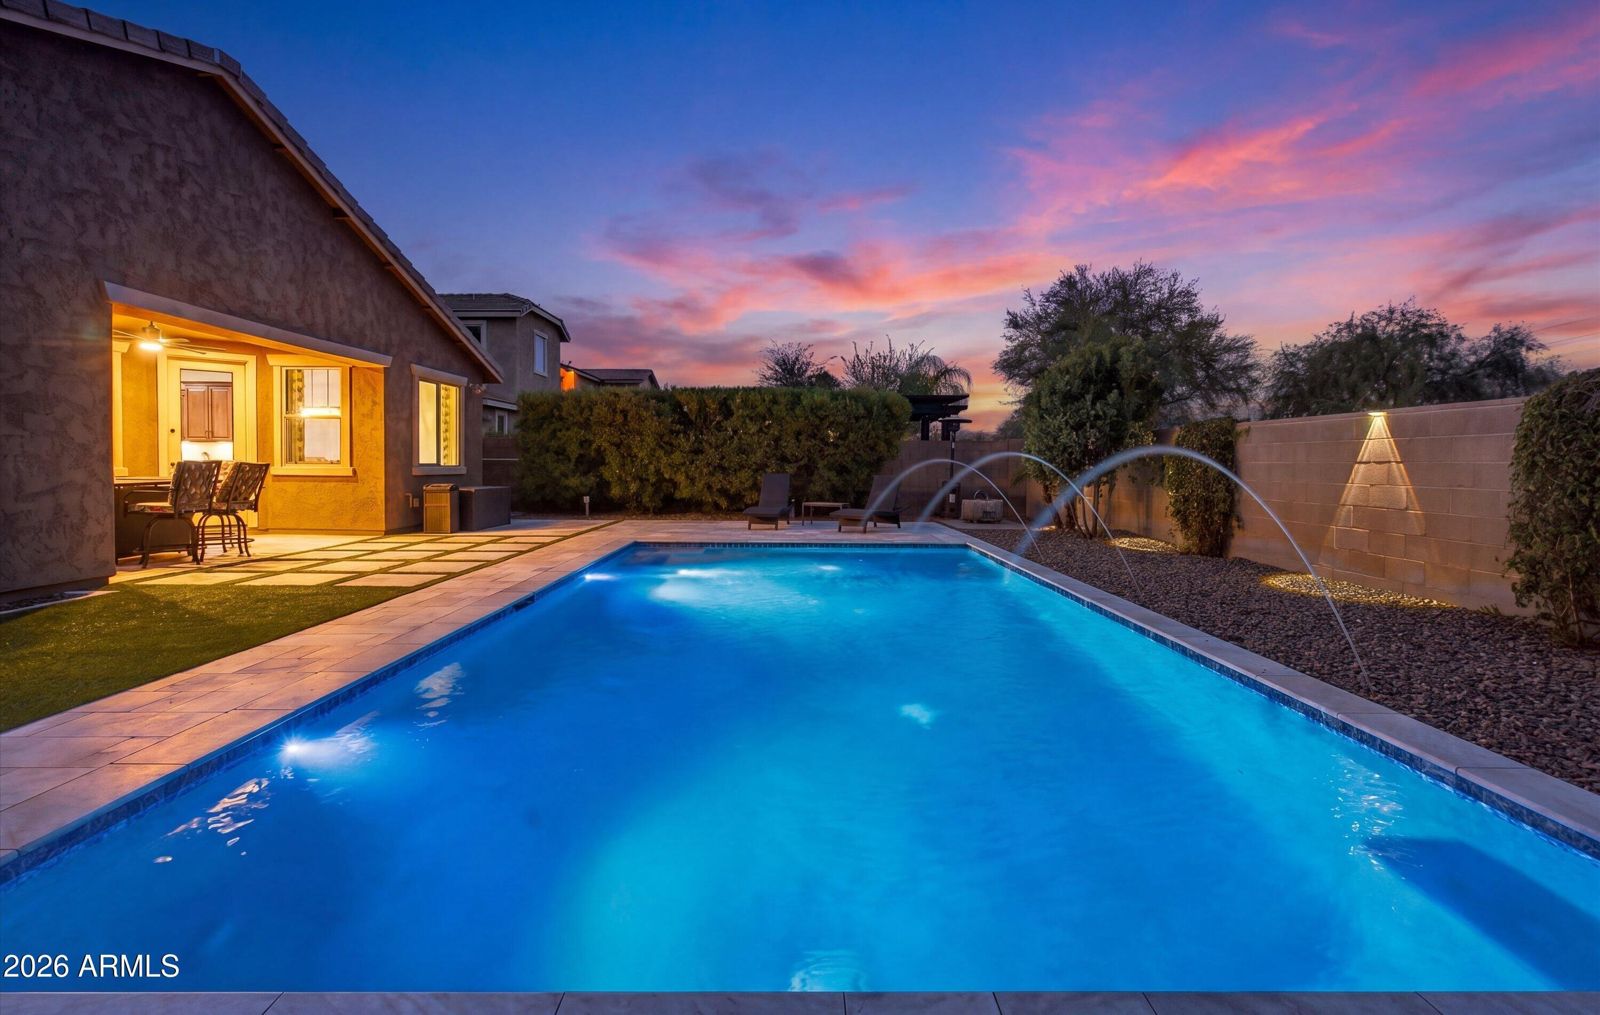
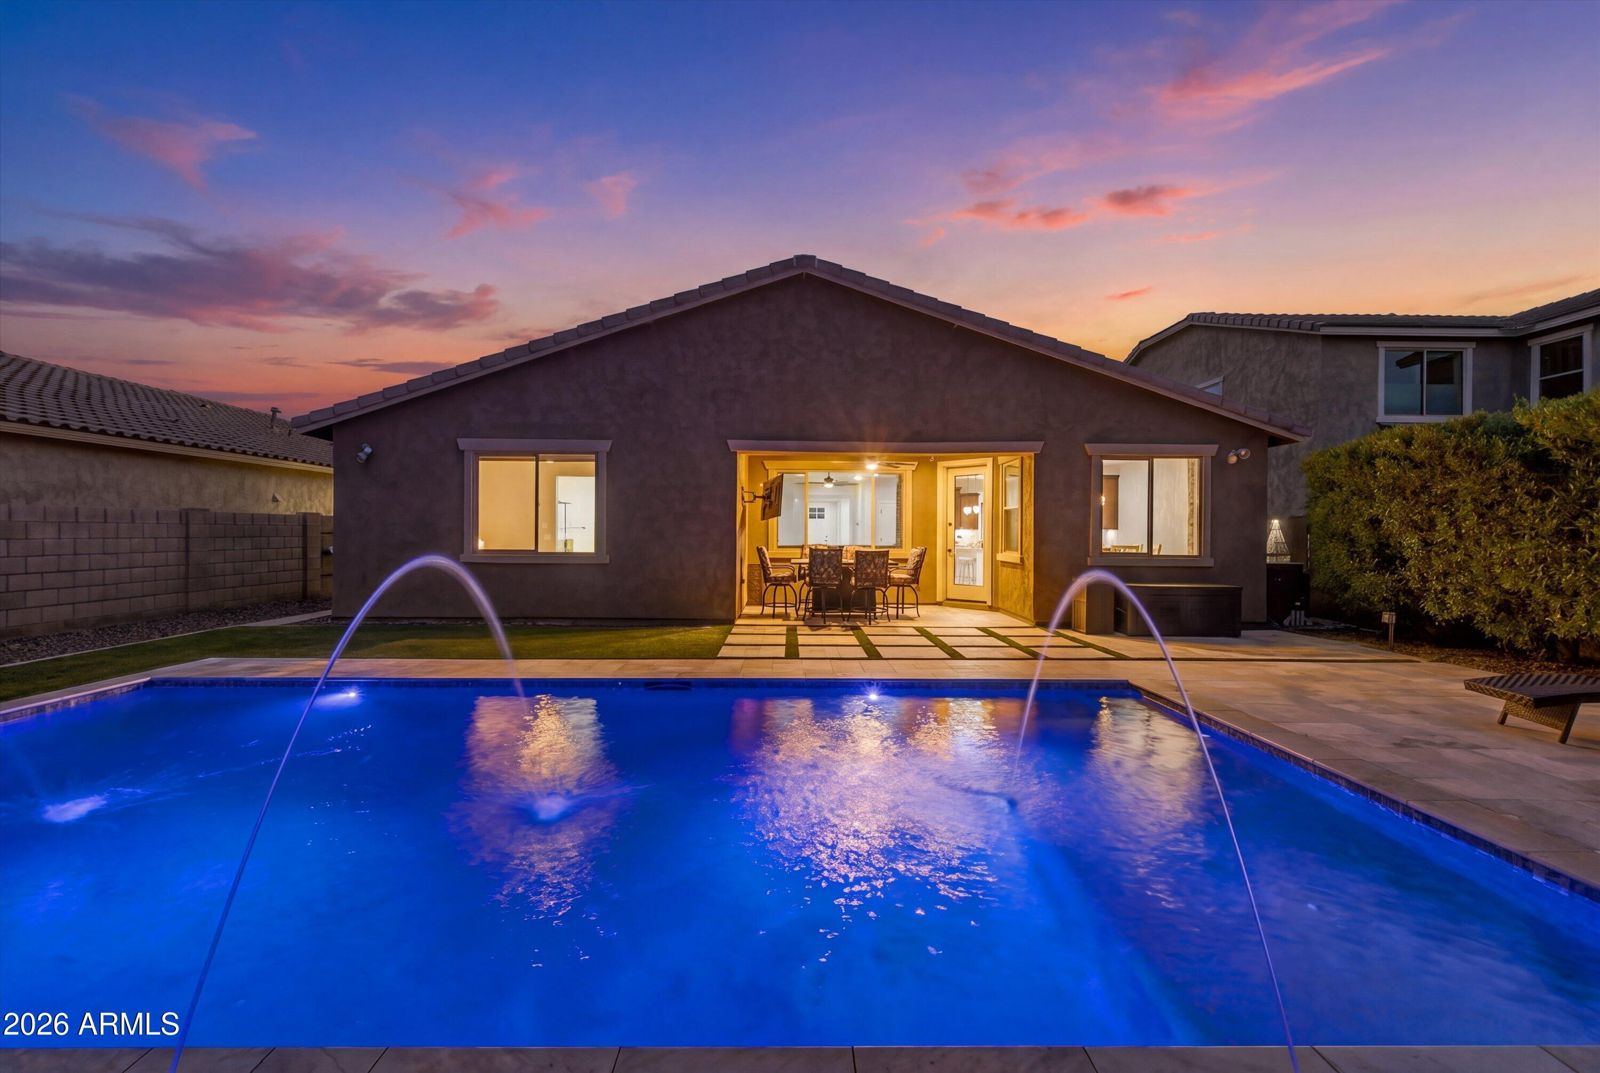
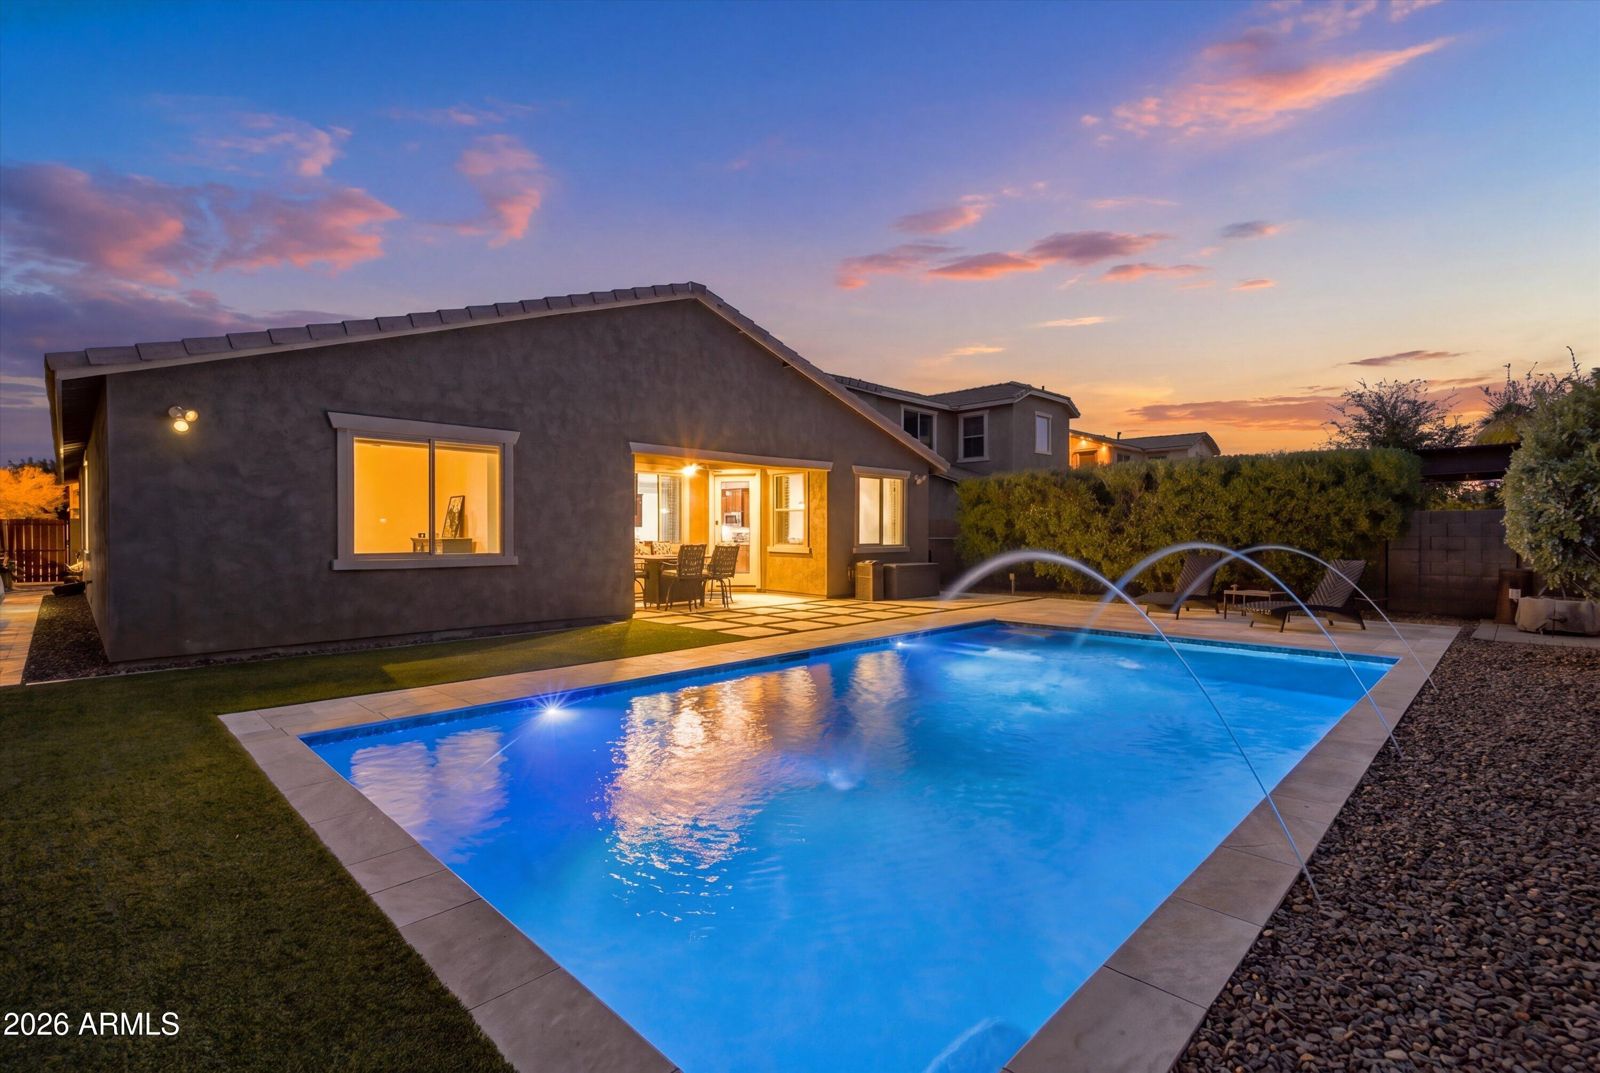
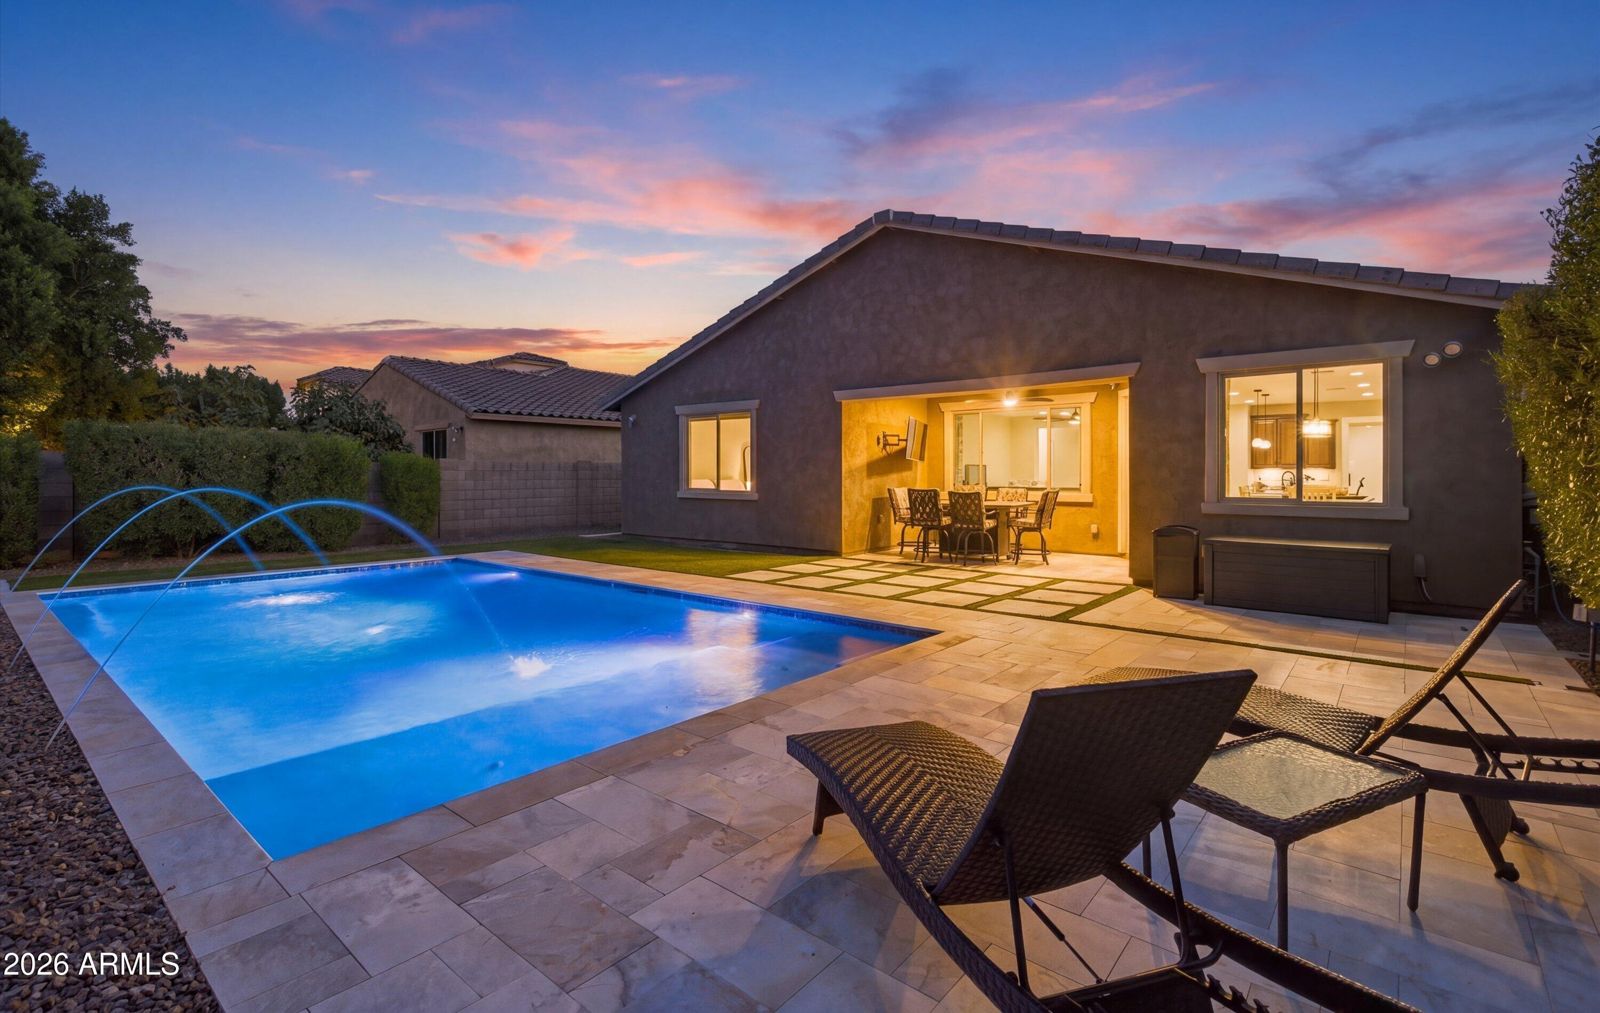
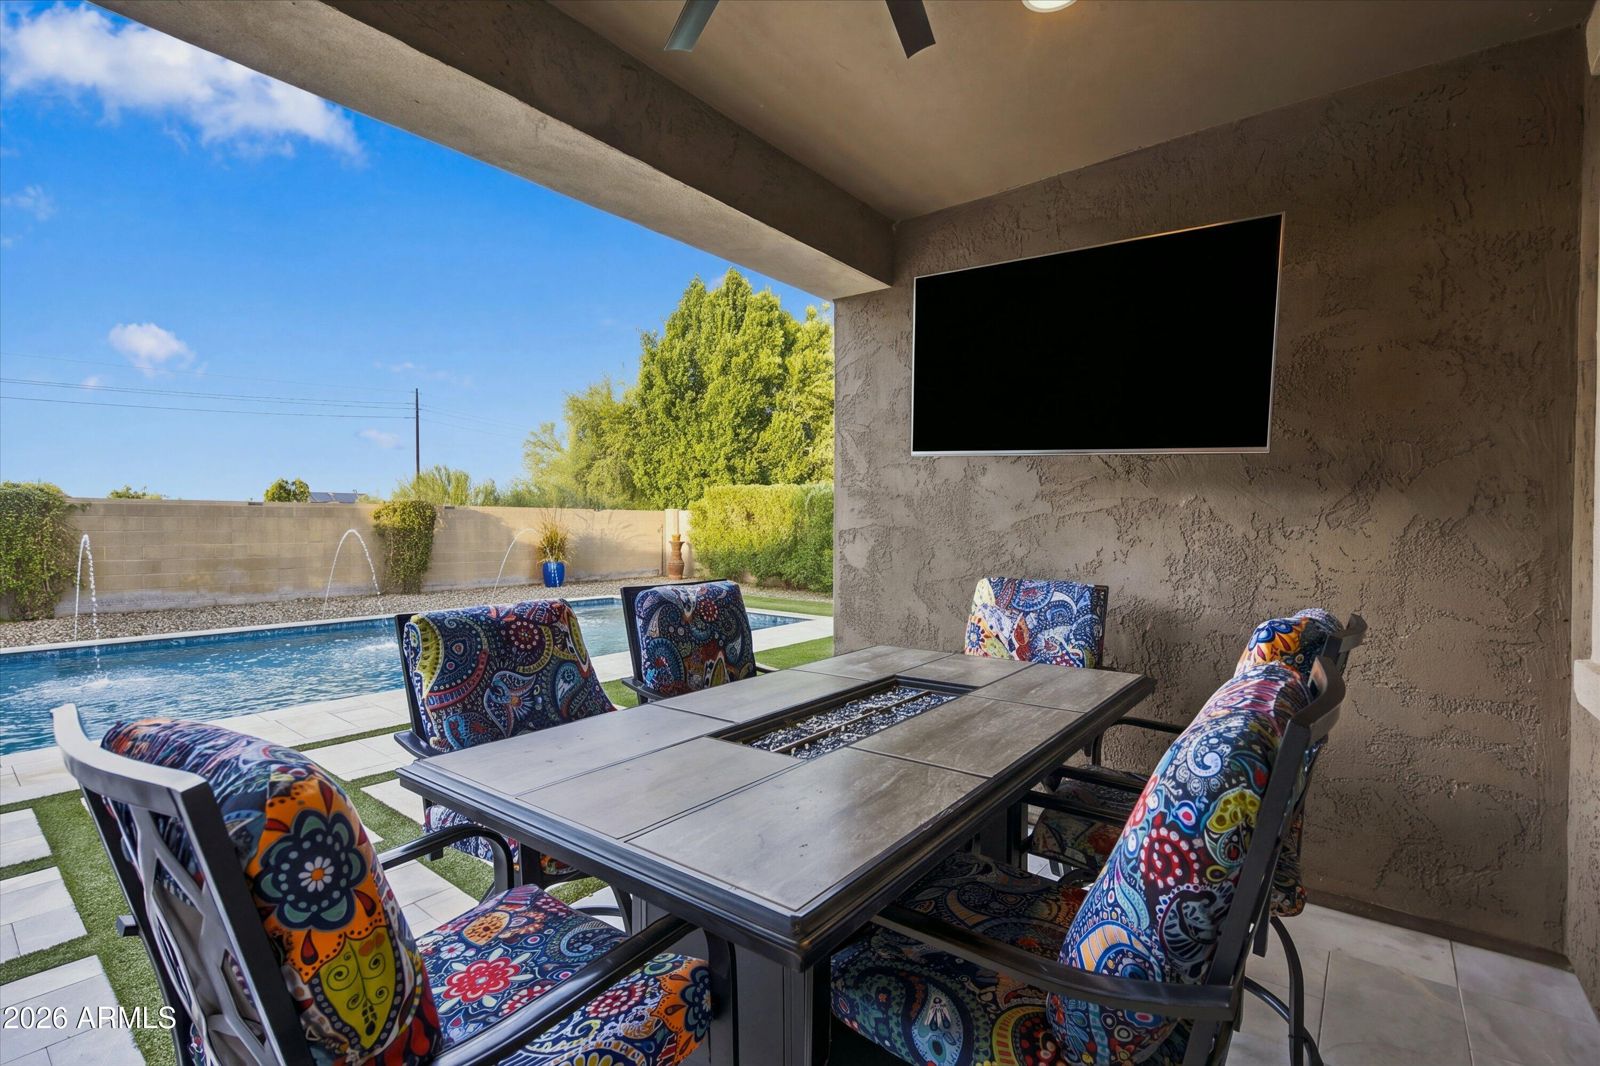
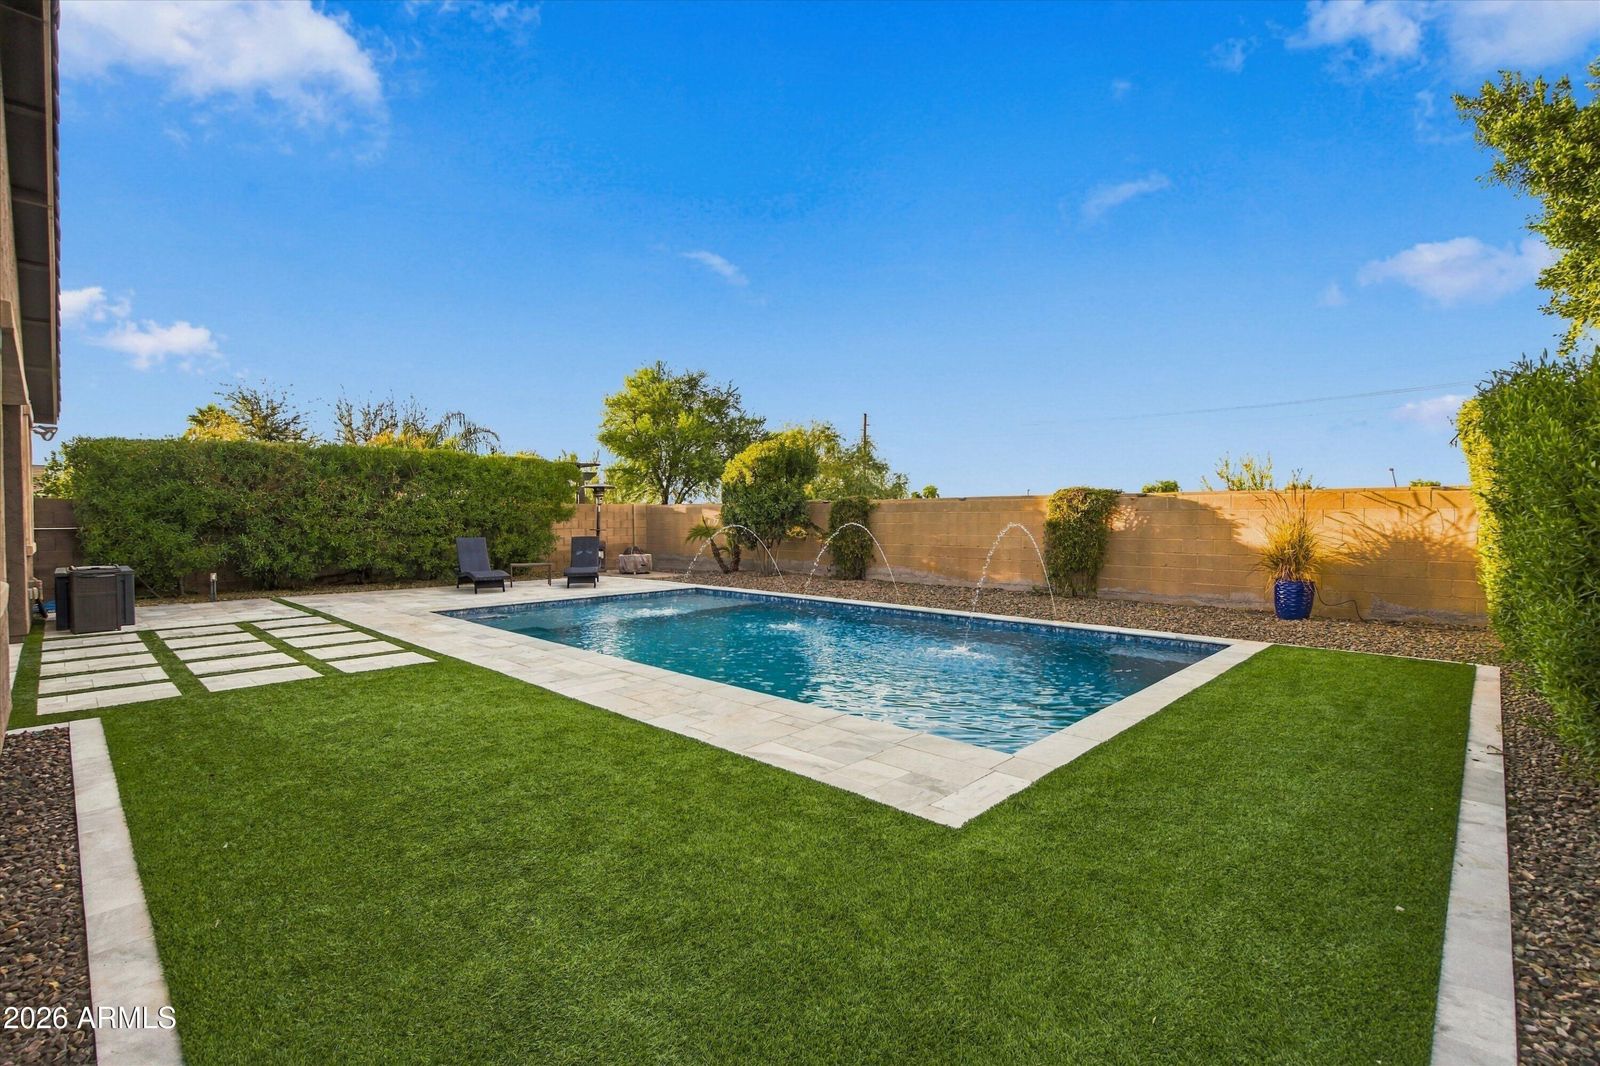
The full listing photo set for 3874 E Strawberry Dr, all 36 photos. The front and rear elevations, the pool and covered patio, the kitchen and great room, the split primary suite, and the flex room are all here.
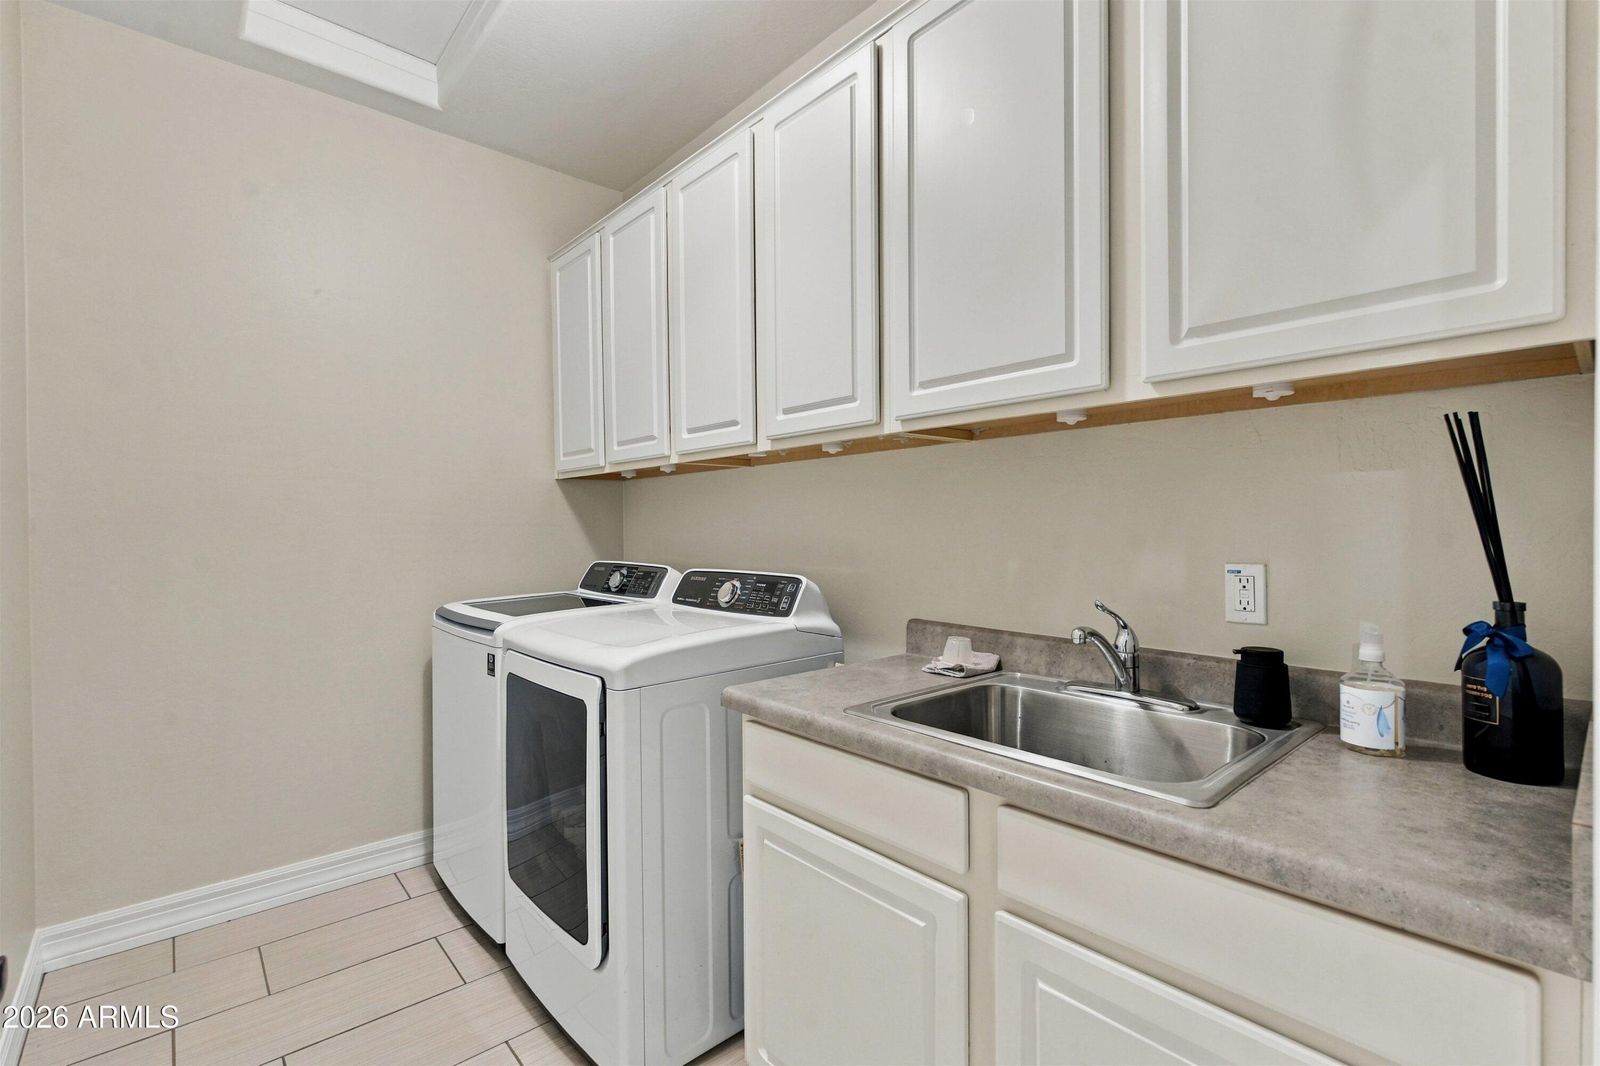
Pool and lawn at sunsetPool with paver decking and covered patioKitchen with island seatingPool at duskFront elevationEntry hallwayFlex room, set up as an officeGreat roomGreat room toward the kitchenGreat room, reverse viewKitchen and great room, wide viewGreat room toward the kitchen islandKitchen, granite counters and dark cabinetryDining area and patio doorDining roomPrimary bedroomPrimary bedroom, second viewPrimary bedroom toward the suite entryPrimary bath, soaking tub and double vanityPrimary bath, glass showerBedroomBedroom with storage bedGuest bath, double vanityBedroom with front windowsBedroom, wide viewBedroom / flex spaceBath, tub and showerLaundry roomPool at dusk, water featuresRear elevation and pool at duskPool and rear patio at duskPool deck at duskFront elevation, paver drivewayCovered patio, outdoor diningBackyard, pool and lawn
Listing photos, ARMLS MLS #7096736.
Inside and out
Single-level Meritage floorplan, 4 bedrooms and 3 baths in 2,411 sq ft, with a huge flex room for an office, game room, or second living space.
Private pool with paver decking and a large covered patio, on a north south lot with no one behind you.
A kitchen built for gathering, stainless steel appliances, abundant cabinetry, and a large walk-in pantry, opening straight into the great room.
Fresh interior paint, custom tile flooring, and brand new Berber carpet, plus a 3-car garage with epoxy floors and built-in overhead storage.
The financing option
Offered at $749,000 in The Bridges at Gilbert, near A+ rated Higley schools, Gilbert Regional Park, and the community lakes and trails.
A 2.00% seller concession ($14,980) written into the offer can fund a 2-1 buydown.
That buydown drops the buyer's payment by about $770 a month in year one. The math is in the next section.
Questions or a tour: call Jason LaFlesch at (602) 369-4663.
The featured financing: a 2-1 buydown
A 2% seller concession can go toward a 2-1 buydown, where the buyer's rate starts 2 points below the note rate in year one and 1 point below in year two. Move any slider and every number on this page recalculates. Defaults match the listing as it stands today, with an example buyer at 20% down and a 7.00% note rate, 30-year fixed, principal and interest only.
Loan at full price
$599,200
after 20% down
Full payment
$3,986
P&I at the note rate
Buydown escrow cost
$13,966
Funded by the concession
Seller net · both options
$734,020
Price minus the concession
The 2-1 buydown escrow costs $13,966 at these settings, so the $14,980 concession funds it in full and leaves about $1,014 for the buyer's other closing costs.
Two ways to spend a $14,980 concession
Written into an offer either way, the seller's dollars are the same and the seller nets the same. The difference is entirely in what the buyer feels month to month.
Option A · Price reduction
Take it off the price
The concession comes off the price instead: $749,000 becomes $734,020. The buyer's loan shrinks by $11,984, so the payment shrinks a little, forever.
$3,907/ mo P&I
Saves the buyer $80/mo
Price after reduction$734,020
Seller dollars used$14,980
Seller net$734,020
Buyer saves over 2 years$1,914
Cash to close$2,996 less down payment
Option B · 2-1 Buydown
Keep the price, buy the rate down
Price stays at $749,000. The same seller dollars fund a 2-1 buydown escrow: the buyer's rate starts 2 points under the note rate, steps up 1 point in year two, then settles at the note rate.
$3,217/ mo P&I in year 1
Saves the buyer $770/mo in year 1
Year 1 · 5.00%
$3,217
save $770/mo
Year 2 · 6.00%
$3,593
save $394/mo
Year 3+ · 7.00%
$3,986
full note payment
Buydown escrow cost$13,966
Concession left overAbout $1,014
Seller dollars used$14,980
Seller net$734,020
Buyer saves over 2 years$13,966
The takeaway: the seller nets $734,020 either way. As a price cut, the $14,980 lowers the buyer's payment by $80 a month. As a buydown, the same dollars lower it by $770 a month in year one, about 9.7× as much. Matching that year-one payment with price alone would take a reduction of roughly $144,644.
At $749,000no buydown
$3,986
Price cut to $734,020Option A
$3,907
Buydown, year 2Option B · 6.00%
$3,593
Buydown, year 1Option B · 5.00%
$3,217
Monthly principal and interest only. Taxes, insurance, HOA, and mortgage insurance are not shown; a price reduction trims them slightly, a buydown does not change them.
Why the buydown works for this home
What buyers actually feel
Buyers shop the monthly payment, not the price. A $3,217 first-year payment reads very differently in a listing conversation than $3,986, and it is the number a payment-sensitive buyer feels month to month.
The relief lands when moving costs hit. The lowest payment comes in the first year, when the buyer is also paying for the move, furniture, and settling in.
The seller keeps their price. Holding the full price protects the appraisal and the neighborhood comp, instead of resetting both lower with a cut.
It gives agents something new to call about. Every agent with a buyer watching this home can now re-contact them with a payment story, not the same listing twice.
The honest trade-offs
The buydown savings are front-loaded. The payment steps up in year two and reaches the full note payment in year three. Buyers should be comfortable at $3,986, not just at $3,217.
Buyers qualify at the full note rate. The buydown lowers the early payments, not the qualifying payment, so it helps cash flow rather than borrowing power.
A price cut lasts forever. It also trims the down payment and slightly lowers taxes and insurance. For a buyer who plans to stay put for decades and never refinance, that permanence has real value.
It is an option, not an either-or. The concession can be split, part buydown and part closing costs, and any leftover after the buydown escrow still goes to the buyer's other closing costs.
How the buydown works in an offer
1
Offer at $749,000 with a 2.00% seller concession
Full list price, with the concession written into the contract as part of the offer.
2
Direct the concession to the buydown
The offer specifies that the seller concession funds a 2-1 buydown escrow with the buyer's lender, with any remainder going to the buyer's other closing costs.
3
The lender holds and applies it
At closing the buydown escrow (about $13,966 at the settings above) is funded from the concession and tops up the buyer's payment each month for the first two years. The seller nets the same as a price cut, and nothing changes for them after closing.